Our team of market analysts have a singular mission: to help you make better investment decisions. Read the latest market commentary.
Continue readingREDDING SCHOOL OF THE ARTS – SERIES 2026 Case Study (September 2026)
HJ Sims Provides $13.215MM in
Bond Financing for BB+ Rated
School in Redding, CA
NMHC Student Housing Conference
HJ Sims is proud to be attending the National Multifamily Housing Council conference.
Attendees: Robert Nickell, Tom Pitcher
Start a Conversation:
Market Commentary: Back Up the Truck
Our team of market analysts have a singular mission: to help you make better investment decisions. Read the latest market commentary.
Continue readingMarket Commentary: All’s Fair
Our team of market analysts have a singular mission: to help you make better investment decisions. Read the latest market commentary.
Continue reading2026 LeadingAge Annual Meeting
HJ Sims is proud to be attending, exhibiting, sponsoring and speaking at the 2026 LeadingAge Annual Meeting.
Come visit us at booth 1315.
Speaking Details:
Lynn Daly, Executive Vice President
Session:
45-F. Affiliate or Go It Alone? Forming Bonds Across Faith Traditions
Phoenix Student Housing & Higher Ed Summit
HJ Sims is proud to be attending, sponsoring and moderating at the Phoenix Student Housing & Higher Ed Summit.
Attendees: Tom Pitcher
Tom Pitcher, Executive Vice President will be moderating at the below panel:
9:05 AM – 10:05 AM: Panel #1: The Campus Equation: How Arizona Colleges Are Planning, Partnering, and Building for Growth
Start a Conversation: [email protected]
NIC Fall Conference
HJ Sims is proud to be attending and sponsoring at the NIC Fall Conference.
Attending:
Aaron Rulnick, Managing Principal, Head of Investment Banking
Curtis King, Executive Vice President
Brady Johnson, Senior Vice President
Brett Edwards, Senior Vice President
Brock Bagelman, Associate
Power of Innovation Summit
HJ Sims is proud to be attending the Power of Innovation Summit.
Attending: Richard Harmon, Executive Managing Director, Head of Education Banking
Market Commentary: Branded For Life
Our team of market analysts have a singular mission: to help you make better investment decisions. Read the latest market commentary.
Continue readingCurve Commentary: September 14, 2026
Overview
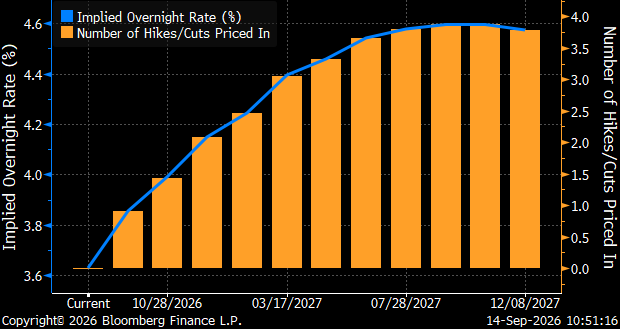
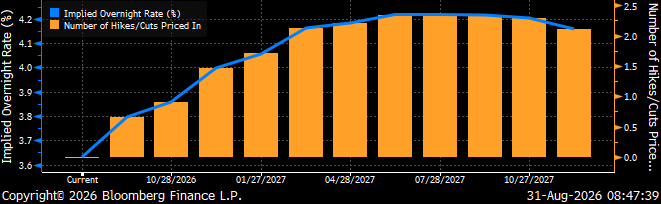
Last week’s CPI data, which surprised markets with a bigger-than-expected increase in prices, has increased the conviction of investors that the Fed needs to hike rates to maintain credibility. Despite Federal Reserve Chairman Warsh’s recent speech at the Jackson Hole symposium, markets are continuing to seek clues regarding the Fed’s plan to bring inflation back to its 2% target. Warsh’s comments were received by the markets as hawkish and have prompted increased bets on a September rate hike. This morning, Fed funds futures are now pricing in the likelihood of a Fed rate hike of 25bp at over 90% for the Fed’s meeting later this week. Furthermore, renewed aggression in Iran is placing upward pressure on oil prices with ICE Brent Futures now approaching $110 per barrel, leading to further speculation about inflation and pushing 10-year Treasury yields to over 5%.
Implied Overnight Rate & Number of Hikes/Cuts
Insights and Strategy
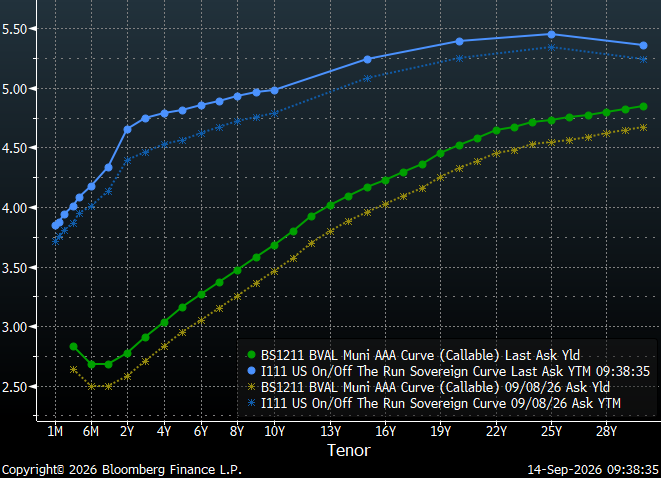
Over this past week, the Treasury curve shifted higher, with the biggest moves around the policy sensitive two-year tenor. Muni yields have moved in a more uniform fashion, with a parallel shift upward of approximately 20 basis points. Inflation fears continue to place upward pressure on longer yields while the anticipation of higher rates from the Fed prop-up yields on the short-end of the yield curve. Despite inflation concerns, the slope at the long-end of the municipal yield curve, past 20-years, remains relatively flat with a total slope of 27 bps from 21-30-years. Due to this flat tail, municipal bond investors can currently buy 20-year maturities that yield over 93% of the 30-year curve.
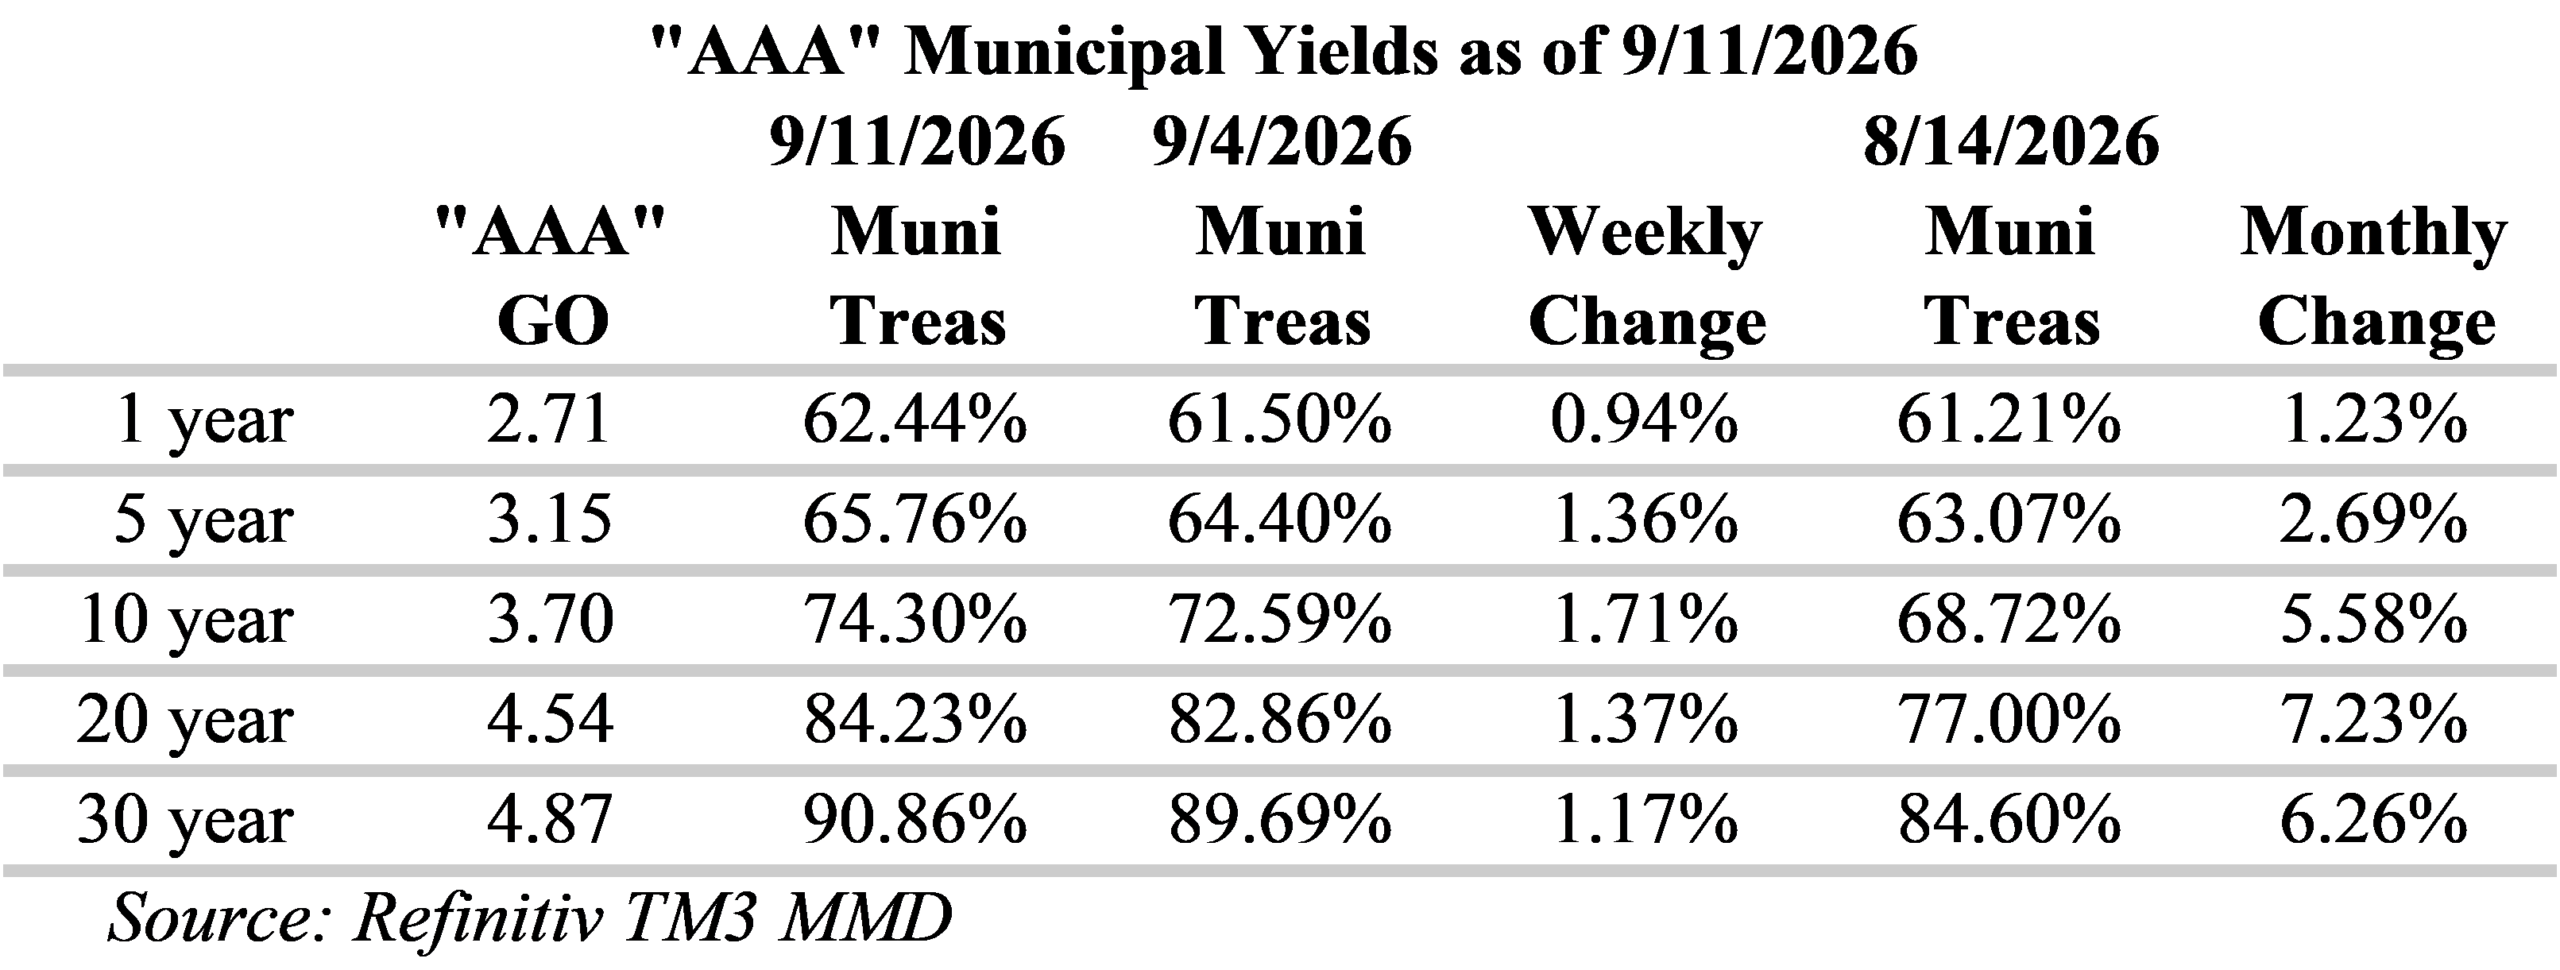
Municipal/Treasury ratios generally increased (cheaper) over this past week, with the largest changes occurring around the 10-year tenor. One-year ratios have now moved decisively over 60%, 10-year ratios are now well over 70% of Treasuries and, due to significant cheapening last week, 20-year ratios are approaching 85%. Investors seeking to maximize curve positioning with relative value can now go to the 14-year tenor and capture over 85% of the 30-year municipal curve with less than half the maturity extension. Furthermore, ratios in this part of the curve are now significantly more appealing at approximately 75% of Treasuries. Flattening further out the curve has made extending maturities less rewarding, but ratios are cheaper with investors capturing over 90% of Treasuries at 30-years. Although, the yield curve is very flat over these longer tenors with just two to three basis points of slope for maturities past 23-years.
Approximately $10.2 billion in new issues are expected to sell in the municipal market this week. Notable deals include: State of New Jersey, which plans to sell $1.67 billion of bonds; Northwell Health Obligated Group has scheduled $734.6 million; County of Hillsborough FL Water & Wastewater Revenue is expected to offer $623.4 million; and, University Health Systems of Eastern Carolina Inc Obligated Group is scheduled to bring $431.1 million to the market. Last week, investors added approximately $193 million to municipal bond mutual funds, up from $138 million the prior week, according to LSEG Lipper data. Furthermore, redemptions and maturities in the next 30-days are expected to total $23.4 billion, according to data compiled by Bloomberg.
Herbert J. Sims & Co. Inc. is a SEC registered broker-dealer, a member of FINRA, SIPC. The information contained herein has been prepared based upon publicly available sources believed to be reliable; however, HJ Sims does not warrant its completeness or accuracy and no independent verification has been made as to its accuracy or completeness. The information contained has been prepared and is distributed solely for informational purposes and is not a solicitation or an offer to buy or sell any security or instrument or to participate in any trading or investment strategy, and is subject to change without notice. All investments include risks. Nothing in this message or report constitutes or should be construed to be accounting, tax, investment or legal advice.
Market Commentary: Home of the Brave
Our team of market analysts have a singular mission: to help you make better investment decisions. Read the latest market commentary.
Continue readingTennessee Charter School Conference
HJ Sims is proud to be attending the Tennessee Charter School Conference.
Attendees: Richard Harmon
Curve Commentary: August 31, 2026
Overview
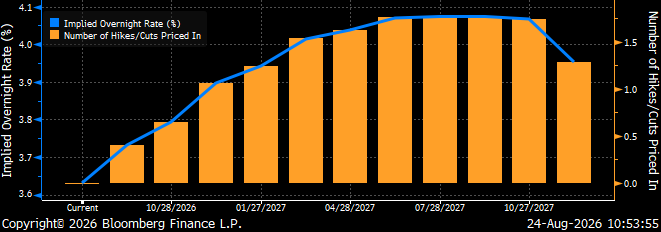
Last week, the capital markets were focused on the Federal Reserve Bank of Kansas City’s annual economic symposium in Jackson Hole, Wyoming. The markets were seeking clarity on the Fed’s economic outlook and looking for clues about its strategy to bring inflation back to target. Although Chairman Warsh did not reveal much, he did reiterate that curbing inflation is the central bank’s top priority and that inflation is not slowing meaningfully. Chairman Warsh also described interest rates as the Fed’s “predominant tool” for controlling inflation. These comments were received by the markets as hawkish and have prompted increased bets on a September rate hike. This morning, Fed funds futures are now pricing in the likelihood of a Fed rate hike of 25bp at over 90% by the October 27-28 meeting. To compound matters, renewed aggression in Iran is placing upward pressure on oil prices leading to further speculation about inflation.
Implied Overnight Rate & Number of Hikes/Cuts
Insights and Strategy
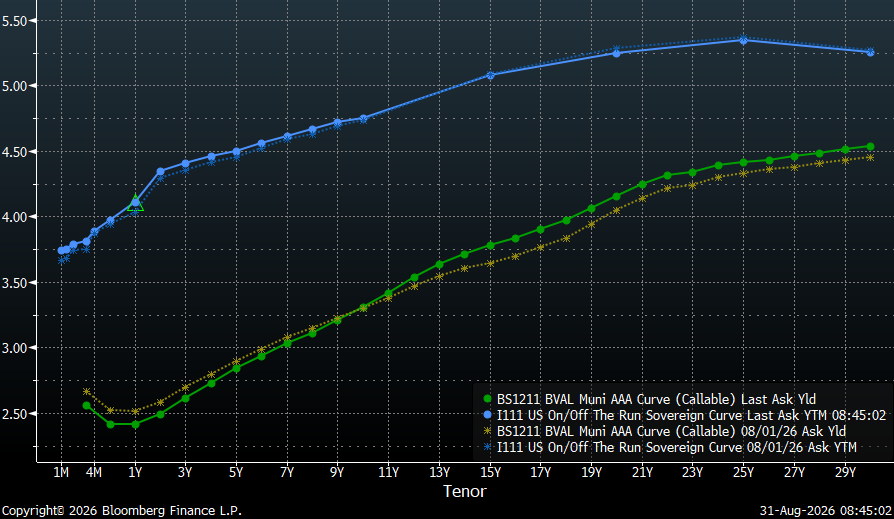
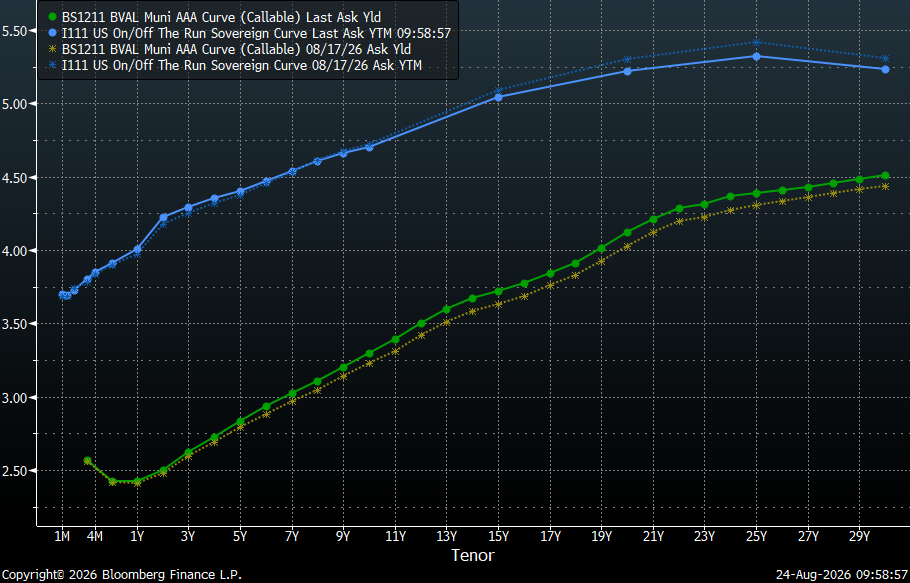
Over this past month, the Treasury curve is largely unchanged, flattened slightly with one-month yields increasing approximately 7 bps and 30-year yields dropping approximately three bps. Muni yields, however, have moved in the opposite direction with a steepening yield curve as long yields sold-off approximately ten basis points and three-month yields rallied a little over four bps. The muni curve rotated around the ten-year tenor with maturities past ten years selling-off and and maturities shorter than ten years rallying. The largest moves in municipals were in the 15-20-year tenors with yields increasing roughly 15bps as heavy issuance, economic uncertainty and inflation fears placed upward pressure on longer yields. Despite these concerns, the slope at the long-end of the municipal yield curve, past 20-years, remains relatively flat with a total slope of 29 bps from 21-30-years. Due to this flat tail, municipal bond investors can currently buy 20-year maturities that yield 91% of the 30-year curve versus 73% for 10-year maturities.
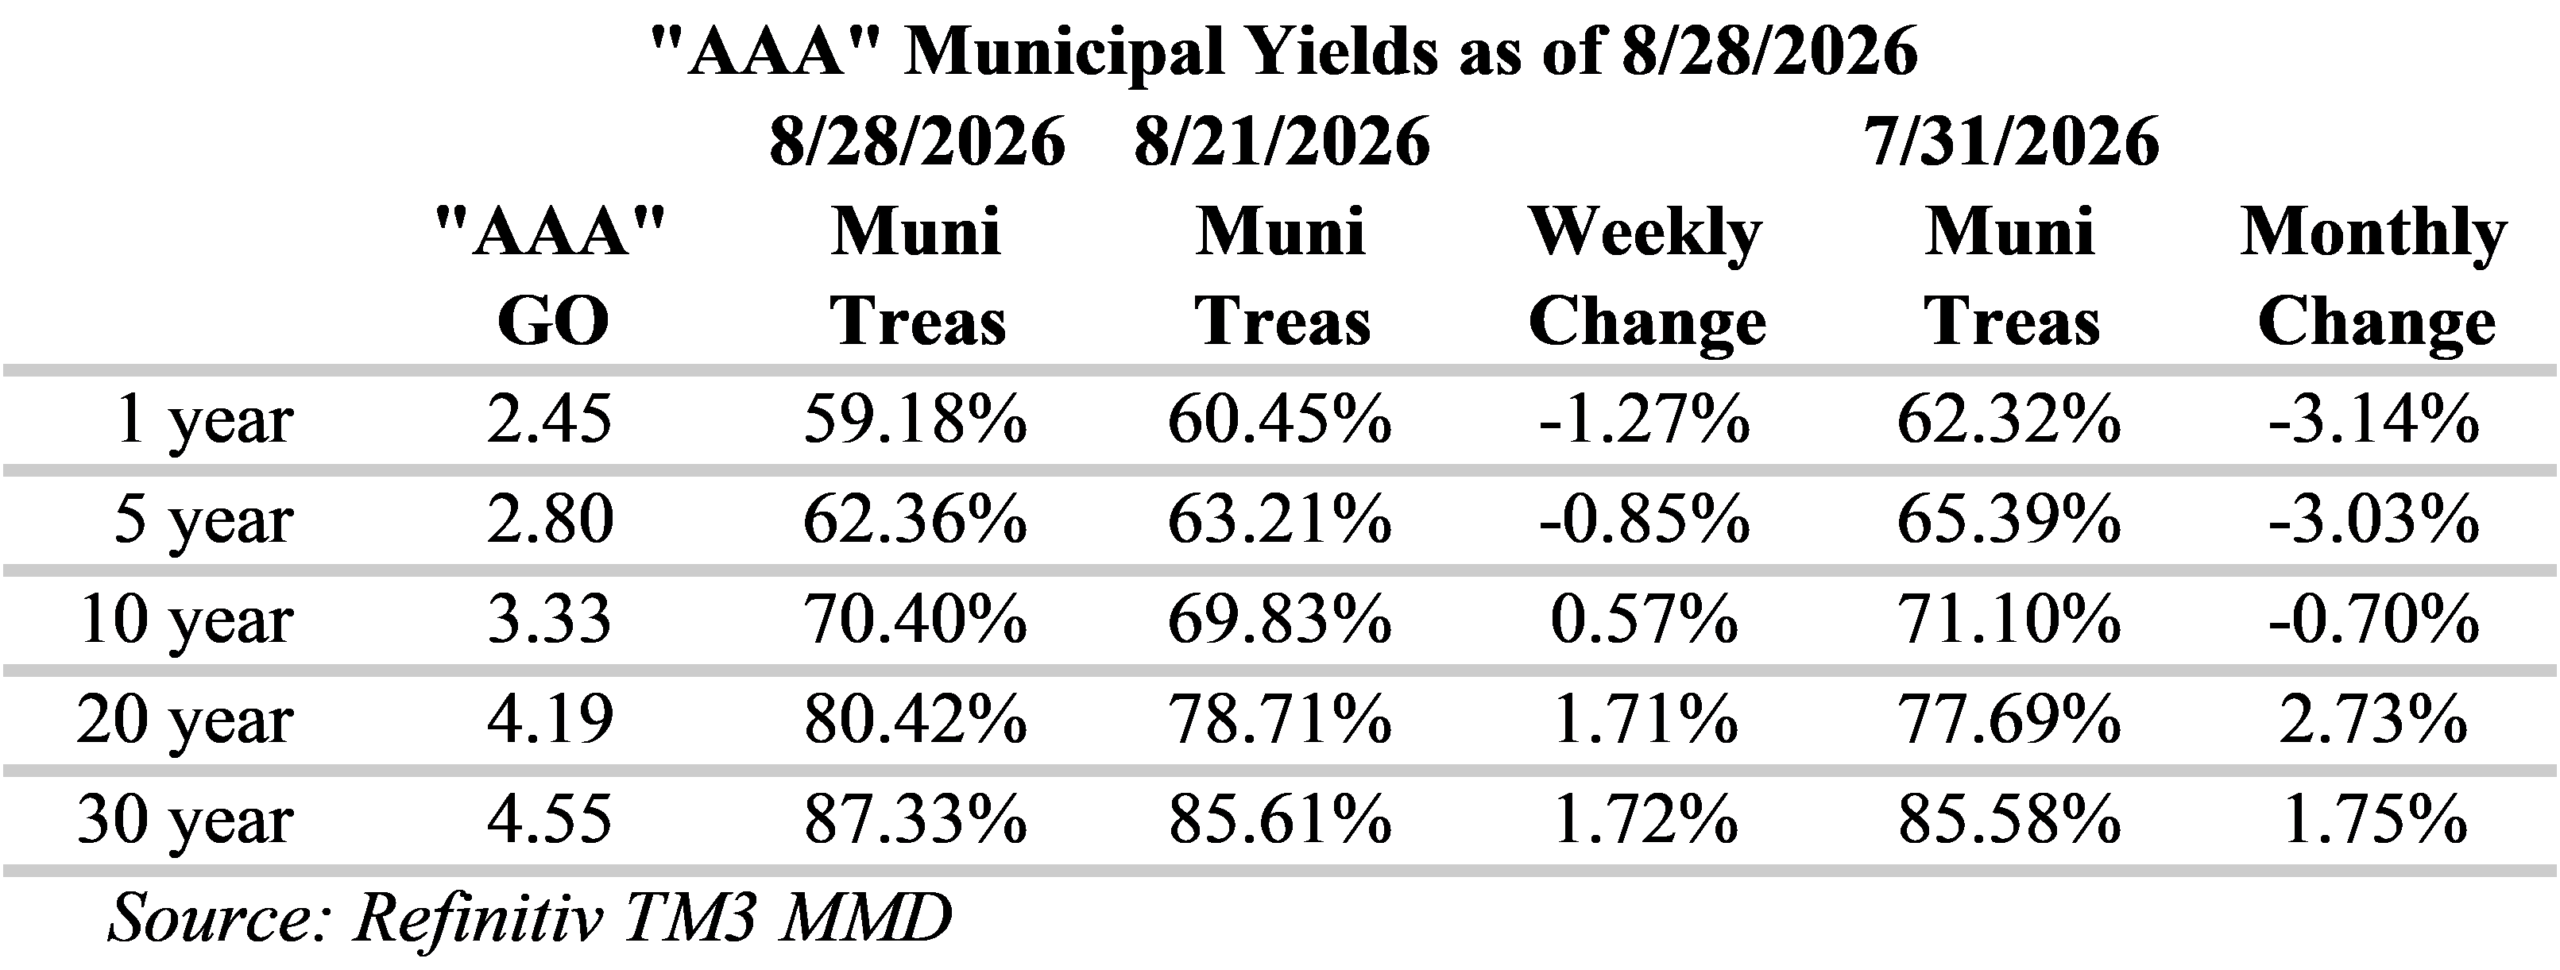
Municipal/Treasury ratios generally increased (cheaper) for maturities past 5-years this past week, with the largest changes occurring past the 20-year tenor. One-year ratios have again dipped below 60%, 10-year ratios tipped over 70% of Treasuries and, due to significant cheapening last week, 20-year ratios are again over 80%. Investors seeking to maximize curve positioning with relative value can now go to the 14-year tenor and capture almost 85% of the 30-year municipal curve with less than half the maturity extension. However, ratios in this part of the curve continue to be a challenge at close to 70% of Treasuries. Flattening further out the curve has made extending maturities less rewarding, but ratios are cheaper with investors capturing over 87% of Treasuries at 30-years. Although, the yield curve is very flat over these longer tenors with just two to three basis points of slope for maturities past 23-years.
The Municipal the new issue calendar picks-up this week from $12.9 billion last week to $15.8 billion. Notable deals include: State of New York Sales Tax Revenue Bonds with $1.93 billion, Salt River Project Agricultural Improvement & Power District has scheduled $1.35 billion, Chicago O’Hare International Airport is expected to offer $1.31 billion and Texas Transportation Commission has $1.12 billion on the calendar. Last week, investors added approximately $1.4 billion to municipal bond mutual funds, up from $838 million the prior week, according to LSEG Lipper data. Furthermore, redemptions and maturities in the next 30-days are expected to total $20.1 billion, according to data compiled by Bloomberg.
Herbert J. Sims & Co. Inc. is a SEC registered broker-dealer, a member of FINRA, SIPC. The information contained herein has been prepared based upon publicly available sources believed to be reliable; however, HJ Sims does not warrant its completeness or accuracy and no independent verification has been made as to its accuracy or completeness. The information contained has been prepared and is distributed solely for informational purposes and is not a solicitation or an offer to buy or sell any security or instrument or to participate in any trading or investment strategy, and is subject to change without notice. All investments include risks. Nothing in this message or report constitutes or should be construed to be accounting, tax, investment or legal advice.
Market Commentary: Snippets
Our team of market analysts have a singular mission: to help you make better investment decisions. Read the latest market commentary.
Continue readingCurve Commentary: August 24, 2026
Overview
Last Wednesday, the Treasury Department announced that it would increase buybacks of long-term bonds through its extended debt repurchase program. The announcement was made after long-term Treasury yields hit the highest levels we have seen on nearly 20-years. The move initially prompted a Treasury market rally, however Treasuries later sold-off as the market questioned the potential impact of increasing buyback operations from $2 billion to at least $4 billion in the $31.5 trillion Treasury market. Furthermore, investors remain cautious amid stubbornly high inflation, mounting federal debt, and a new Federal Reserve chairman inclined to remain quiet. Fed funds futures are now pricing in the likelihood of a Fed rate hike of 25bp at over 100% by the December 8-9 meeting; which, as of earlier this month, was thought to occur as soon as October. Furthermore, this week bond traders will be paying attention to the GDP and personal consumption expenditures price index on Wednesday and Kevin Warsh’s first Jackson Hole Economic Policy Summit as Fed Chairman.
Implied Overnight Rate & Number of Hikes/Cuts
Insights and Strategy
Over this past week, the Treasury curve experienced a rally on the long-end while municipal bonds sold-off for periods past 4-years. Recent issuance trends and adjustments to yield slopes have resulted in the intermediate portion of the municipal yield curve having more slope. While inflation concerns, driven by volatile energy prices, continue to hold the long-end of the Treasury curve above 5% for maturities past 15-years. The slope at the long-end of the municipal yield curve, past 20-years, remains relatively flat with a total slope of 28 bps from 21-30-years. Due to this flat tail, municipal bond investors can currently buy 20-year maturities that yield 91% of the 30-year curve versus 73% for 10-year maturities.
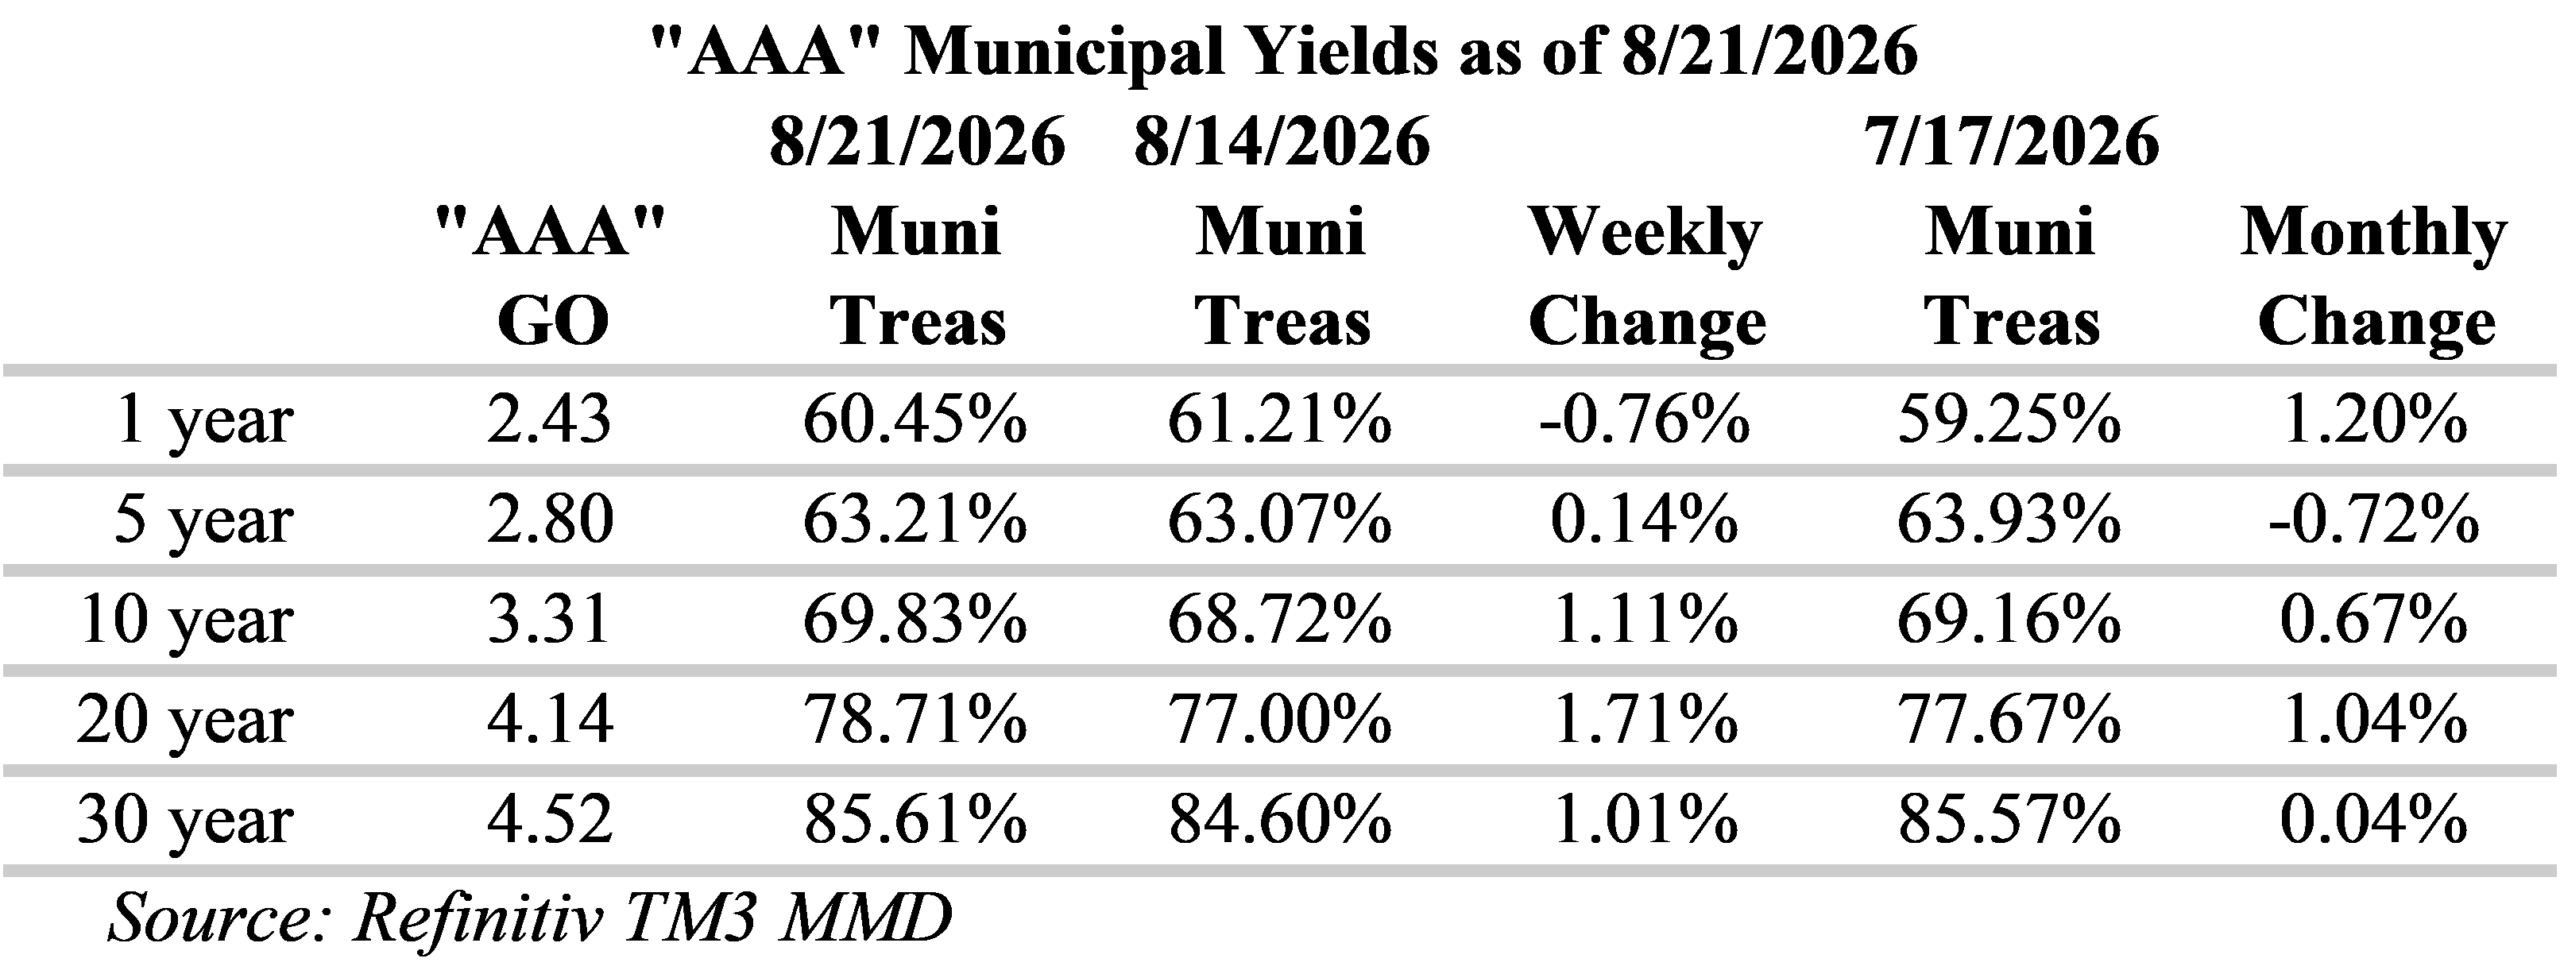
Not surprisingly, municipal/Treasury ratios have generally increased (cheaper) this past week, with the largest changes occurring around the 20-year tenor. One-year ratios continue to hover over 60%, 10-year ratios remain just under 70% of Treasuries and, despite significant cheapening last week, 20-year ratios remain just below 80%. Investors seeking to maximize curve positioning with relative value can now go to the 13-year tenor and capture over 80% of the 30-year municipal curve. However, ratios in this part of the curve continue to be a challenge at approximately 70% of Treasuries. Flattening further out the curve has made extending maturities less rewarding, but ratios are cheaper with investors capturing over 85% of Treasuries at 30-years. Although, the yield curve is very flat over these longer tenors with just two to three basis points of slope for maturities past 23-years.
The Municipal the new issue calendar drops this week from $17.4 billion last week to a more palatable, but still robust $12.9 billion. Notable deals include: the City of Portland, which plans to sell $585.6 million of water system revenue bonds; the Commonwealth of Pennsylvania has scheduled $533.6 million; City of San Antonio, Texas is expected to offer $488 million; and, Pennsylvania State University is on the calendar with $458.4 million. Last week, investors added approximately $838 million to municipal bond mutual funds, up from $758 million the prior week, according to LSEG Lipper data. Furthermore, redemptions and maturities in the next 30-days are expected to total $22.5 billion, according to data compiled by Bloomberg. Overall, investors continue to support munis but opportunities along the yield curve are currently favoring shorter strategies.
Herbert J. Sims & Co. Inc. is a SEC registered broker-dealer, a member of FINRA, SIPC. The information contained herein has been prepared based upon publicly available sources believed to be reliable; however, HJ Sims does not warrant its completeness or accuracy and no independent verification has been made as to its accuracy or completeness. The information contained has been prepared and is distributed solely for informational purposes and is not a solicitation or an offer to buy or sell any security or instrument or to participate in any trading or investment strategy, and is subject to change without notice. All investments include risks. Nothing in this message or report constitutes or should be construed to be accounting, tax, investment or legal advice.
Curve Commentary: August 17, 2026
Overview
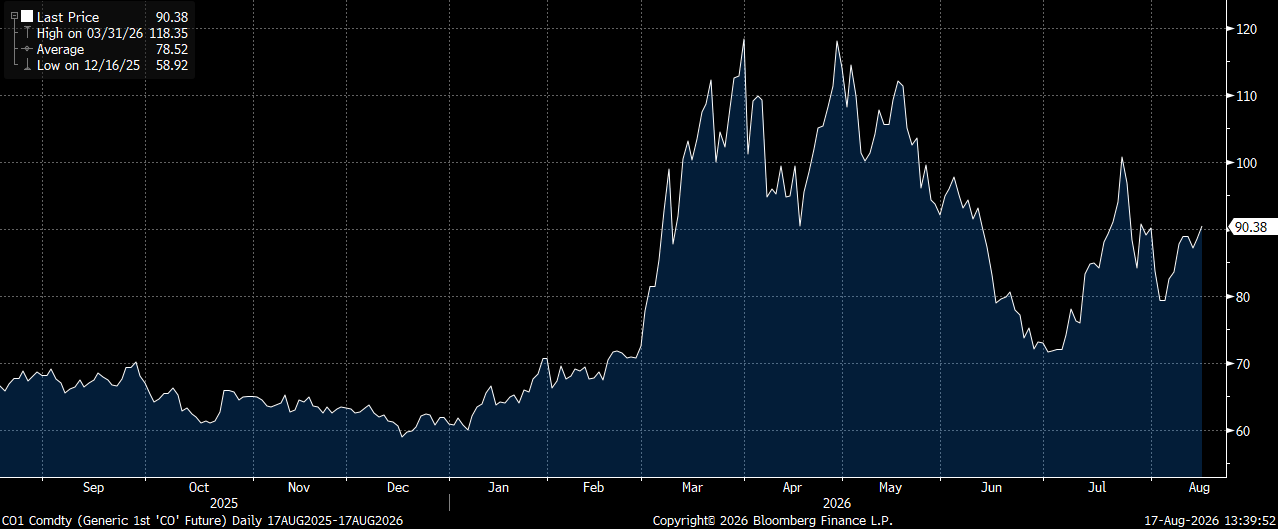
The yield on 30-year Treasuries hit the highest level since 2007 today as investors struggle with inflationary pressures amid inflation that has exceeded the Fed’s target 2% rate for the past five-years. Although both CPI and PPI prints from last week were better than economists had forecast, surging government spending amid stubborn inflation and faint prospects of peace in Iran have markets nervous. In addition, energy prices continue to creep-up, with restricted oil traffic through the Strait of Hormuz. ICE Brent Futures are now back in the low $90’s. Furthermore, the last Fed meeting has left many market participants unconvinced of the Fed’s commitment to fighting inflation. The impression of a stable labor market combined with elevated energy prices continues to sustain a narrative for Fed rate hikes later this year. Fed funds futures are now pricing in the likelihood of a Fed rate hike of 25bp at 96% by the December 8-9 meeting; which, as of earlier this month, was thought to occur as soon as October.
ICE Brent Crude Oil Futures
Insights and Strategy
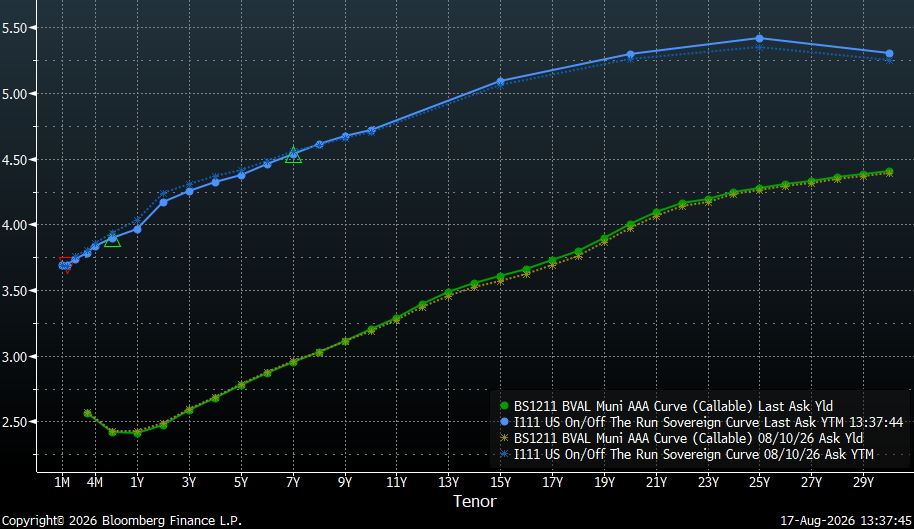
Over this past week, the Treasury curve is relatively unchanged, with some movement around the policy sensitive two-year tenor and some inflation fueled steepening on the long-end. By comparison, municipal yields have been more stable with ratios driving yields up a bit around the 15 to 20-year tenors. Inflation concerns with volatile energy prices continue to hold the long-end of the Treasury curve above 5% for maturities past 15-years. The slope at the long-end of the municipal yield curve, past 20-years, remains relatively flat with a total slope of 30 bps from 21-30-years. Due to this flat tail, municipal bond investors can currently buy 20-year maturities that yield 91% of the 30-year curve versus 73% for 10-year maturities.
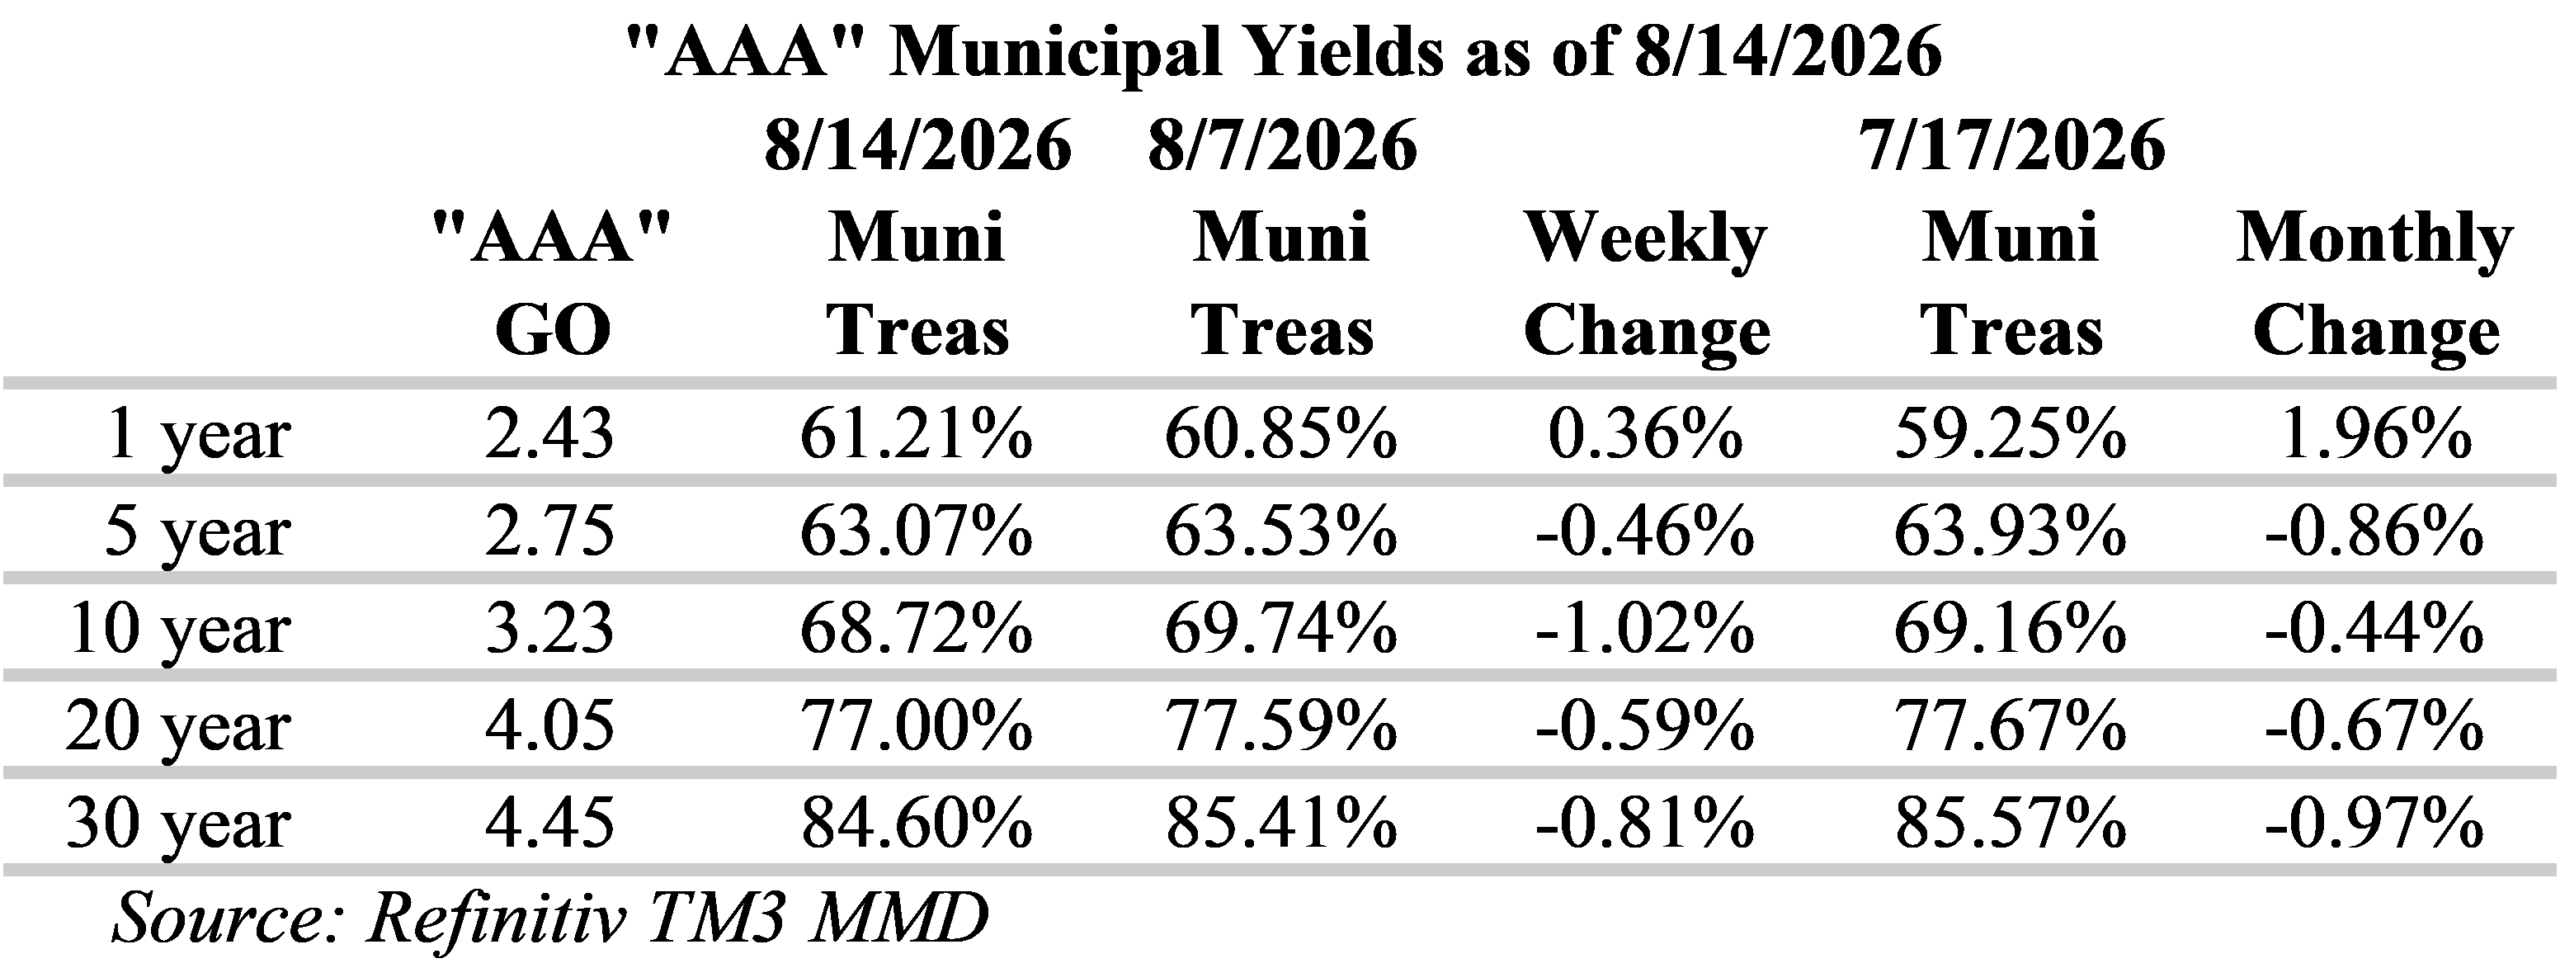
Municipal/Treasury ratios have generally declined (richer) this past week, with the largest changes occurring around the 10-year tenor. One-year ratios are now just above 60% and 10-year ratios remain under 70% of Treasuries and 20-year ratios remain just below 80%. Recent adjustments to yield slopes have resulted in the intermediate portion of the yield curve having more slope. Investors seeking to maximize curve positioning with relative value can now go to the 13-year tenor and capture approximately 80% of the 30-year municipal curve. However, ratios in this part of the curve continue to be a challenge at approximately 70% of Treasuries. Flattening further out the curve has made extending maturities less rewarding, but ratios are cheaper with investors capturing 85% of Treasuries at 30-years. Although, the yield curve is very flat over these longer tenors with just two to three basis points of slope for maturities past 23-years.
The Municipal the new issue calendar ramps-up again this week with US state and local governments expected to sell around $17.4 billion of bonds. Notable deals include: the City of Los Angeles Department of Airports with $2.71 billion; New York City Transitional Finance Authority Future Tax Secured Revenue has scheduled $1.92 billion; State of Michigan Trunk Line Revenue is expected to offer $706.4 million; and, Los Angeles County Metropolitan Transportation Authority is scheduled to bring $530.6 million to market. Last week, investors added approximately $758 million to municipal bond mutual funds, down from $1.3 billion the prior week, according to LSEG Lipper data. Furthermore, redemptions and maturities in the next 30-days are expected to total $24.3 billion, according to data compiled by Bloomberg. Overall, investors continue to support munis but relative value versus Treasuries is becoming a more significant factor.
Herbert J. Sims & Co. Inc. is a SEC registered broker-dealer, a member of FINRA, SIPC. The information contained herein has been prepared based upon publicly available sources believed to be reliable; however, HJ Sims does not warrant its completeness or accuracy and no independent verification has been made as to its accuracy or completeness. The information contained has been prepared and is distributed solely for informational purposes and is not a solicitation or an offer to buy or sell any security or instrument or to participate in any trading or investment strategy, and is subject to change without notice. All investments include risks. Nothing in this message or report constitutes or should be construed to be accounting, tax, investment or legal advice.
Market Commentary: The Largest Room
Our team of market analysts have a singular mission: to help you make better investment decisions. Read the latest market commentary.
Continue readingLeadingAge PA Fall Finance Conference
HJ Sims is proud to be attending, sponsoring, speaking and exhibiting at the LeadingAge PA Fall Finance Conference.
Speaking Details
Date/Time: October 7, 2026 at 2:15pm-3:15pm
Jim Bodine and Steven Hicks of HJ Sims will join Anne Hamilton Taylor of Truist for “Senior Living Financing – Bank Financing Opportunities and Dynamics.”
Date/Time: October 8, 2026 at 1pm-2pm
Jim Bodine of HJ Sims will join Dan Novelli and Jacob Riggs, CFA of LCS for “Building What’s Next: Your 5-Year Window in Aging Services.”
Attendees
James Bodine
Executive Vice President
HJ Sims
(267) 360-6245
[email protected]
Steven Hicks
Vice President
HJ Sims
(240) 207-1155
[email protected]
Market Commentary: NIMBY
Our team of market analysts have a singular mission: to help you make better investment decisions. Read the latest market commentary.
Continue reading