Curve Commentary: July 20, 2026

Overview

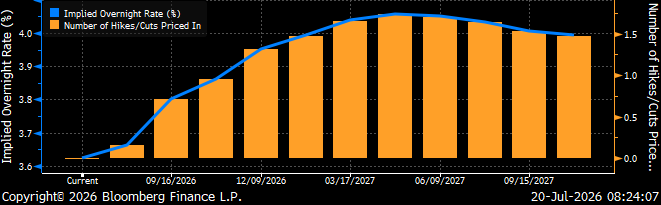
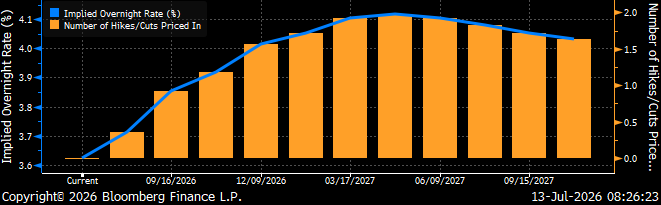
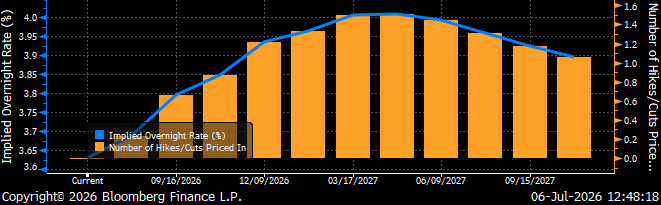
This morning, the war in Iran continues to make headlines amid the possibility of a 10-day ceasefire.  With shipping traffic through the Strait of Hormuz reportedly at a virtual standstill, we are seeing some relief in oil prices this morning as optimism lifts for a potential peace deal.  Last week, reports on US consumer and producer prices, came in much cooler than economists expected.  This is important because these are the final inflation prints this month before the Fed’s meeting next week.  As a result, Fed funds futures are now pricing in a Fed rate hike of 25bp by the October 27-28 meeting (97.5%); which, was previously thought to occur as soon as September.  The current outlook for Fed policy has shifted from two quarter-point hikes by mid-2027, to one hike this year and possibly none next year with declining likelihood starting in June 2027.

Implied Overnight Rate & Number of Hikes/Cuts
Insights and Strategy

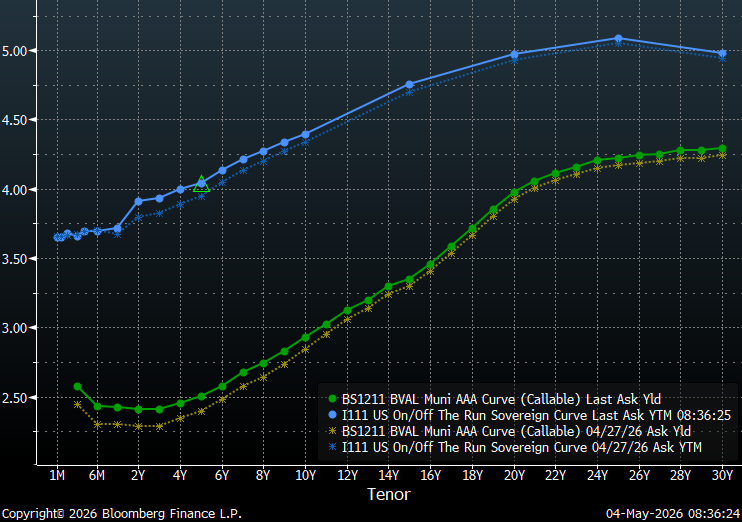
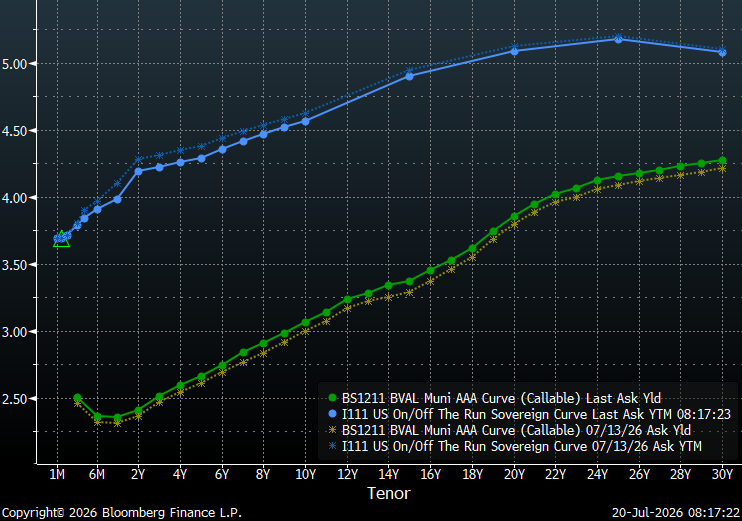
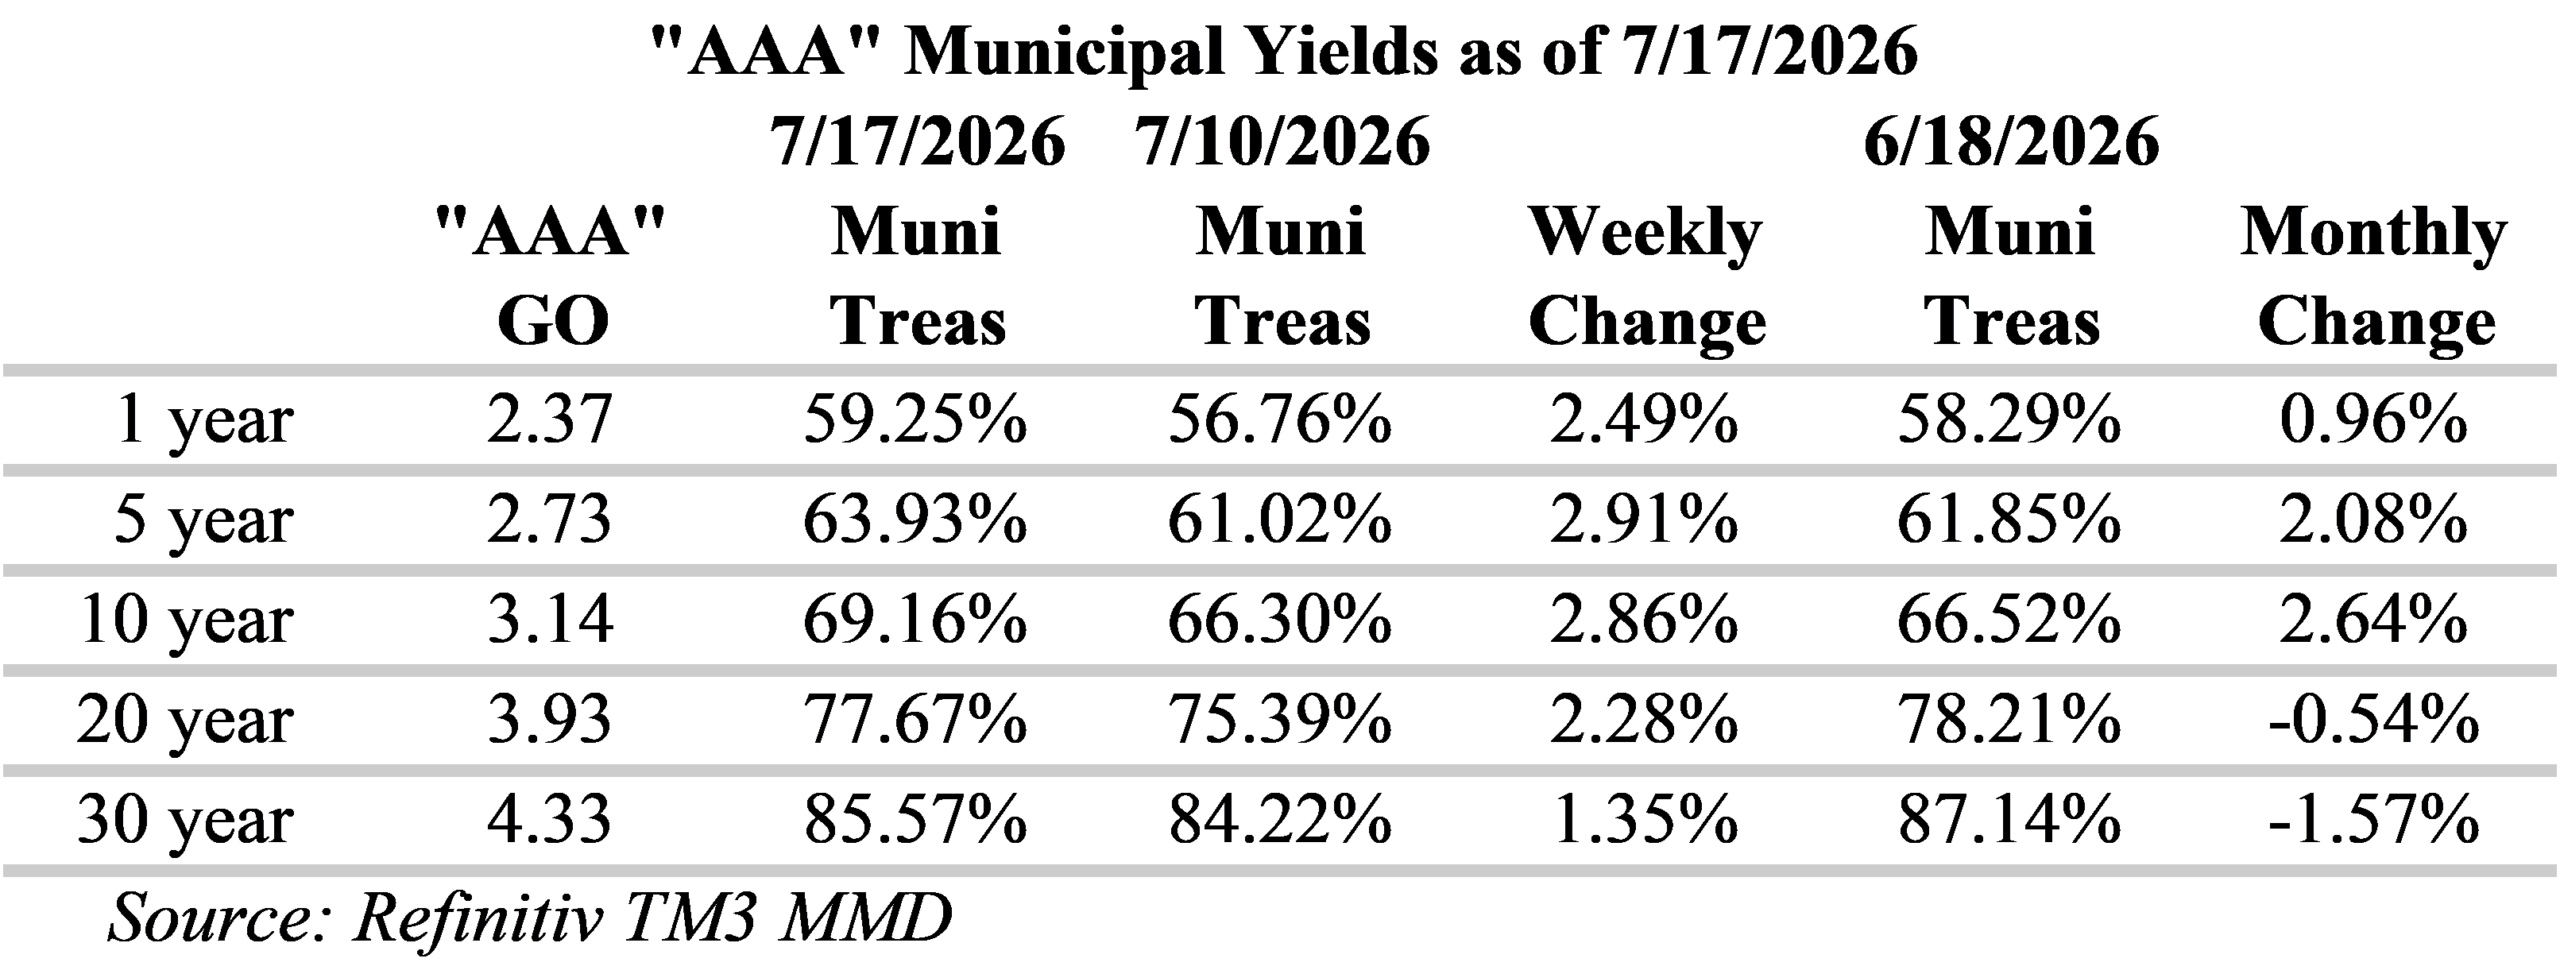
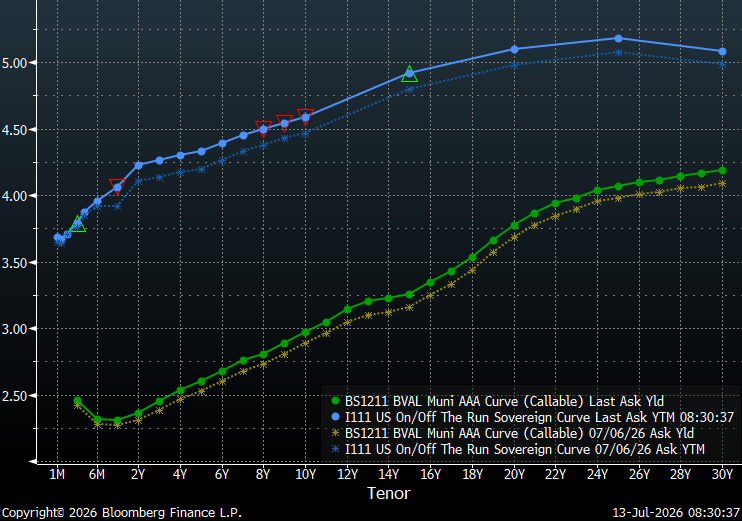
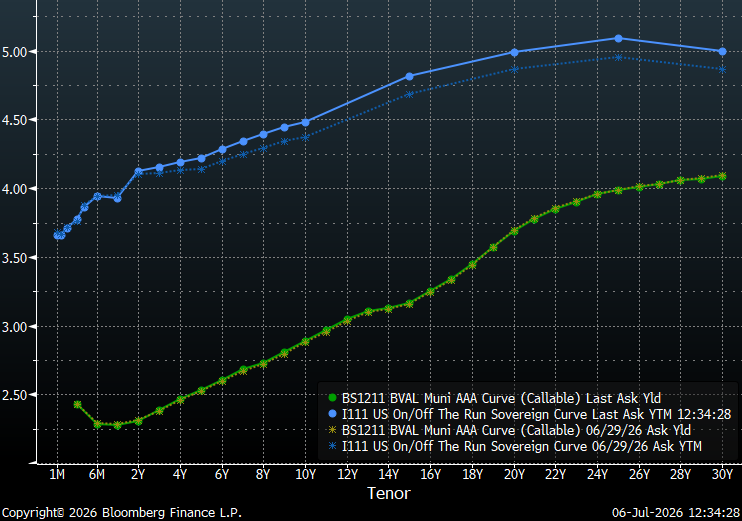
In response to last week’s inflation news, the Treasury curve dipped around the policy sensitive two-year tenor while the municipal yield curve shifted higher in response to technical factors.  Inflation concerns with volatile energy prices continue to hold the long-end of the Treasury curve above 5% for maturities past 20-years.  When comparing the municipal yield curve to the Treasury curve, the first 6 months immediately stand-out with the inverted shape of the municipal curve sharply contrasting with the steeply sloped Treasury curve.  Also, as discussed in greater detail below, record issuance and rich ratios are creating some resistance in munis.  The slope at the long-end of the municipal yield curve, past 20-years, remains relatively flat with a total slope of 30 bps from 21-30-years.  Due to this flat tail, municipal bond investors can currently buy 20-year maturities that yield almost 91% of the 30-year curve versus 72.5% for 10-year maturities.
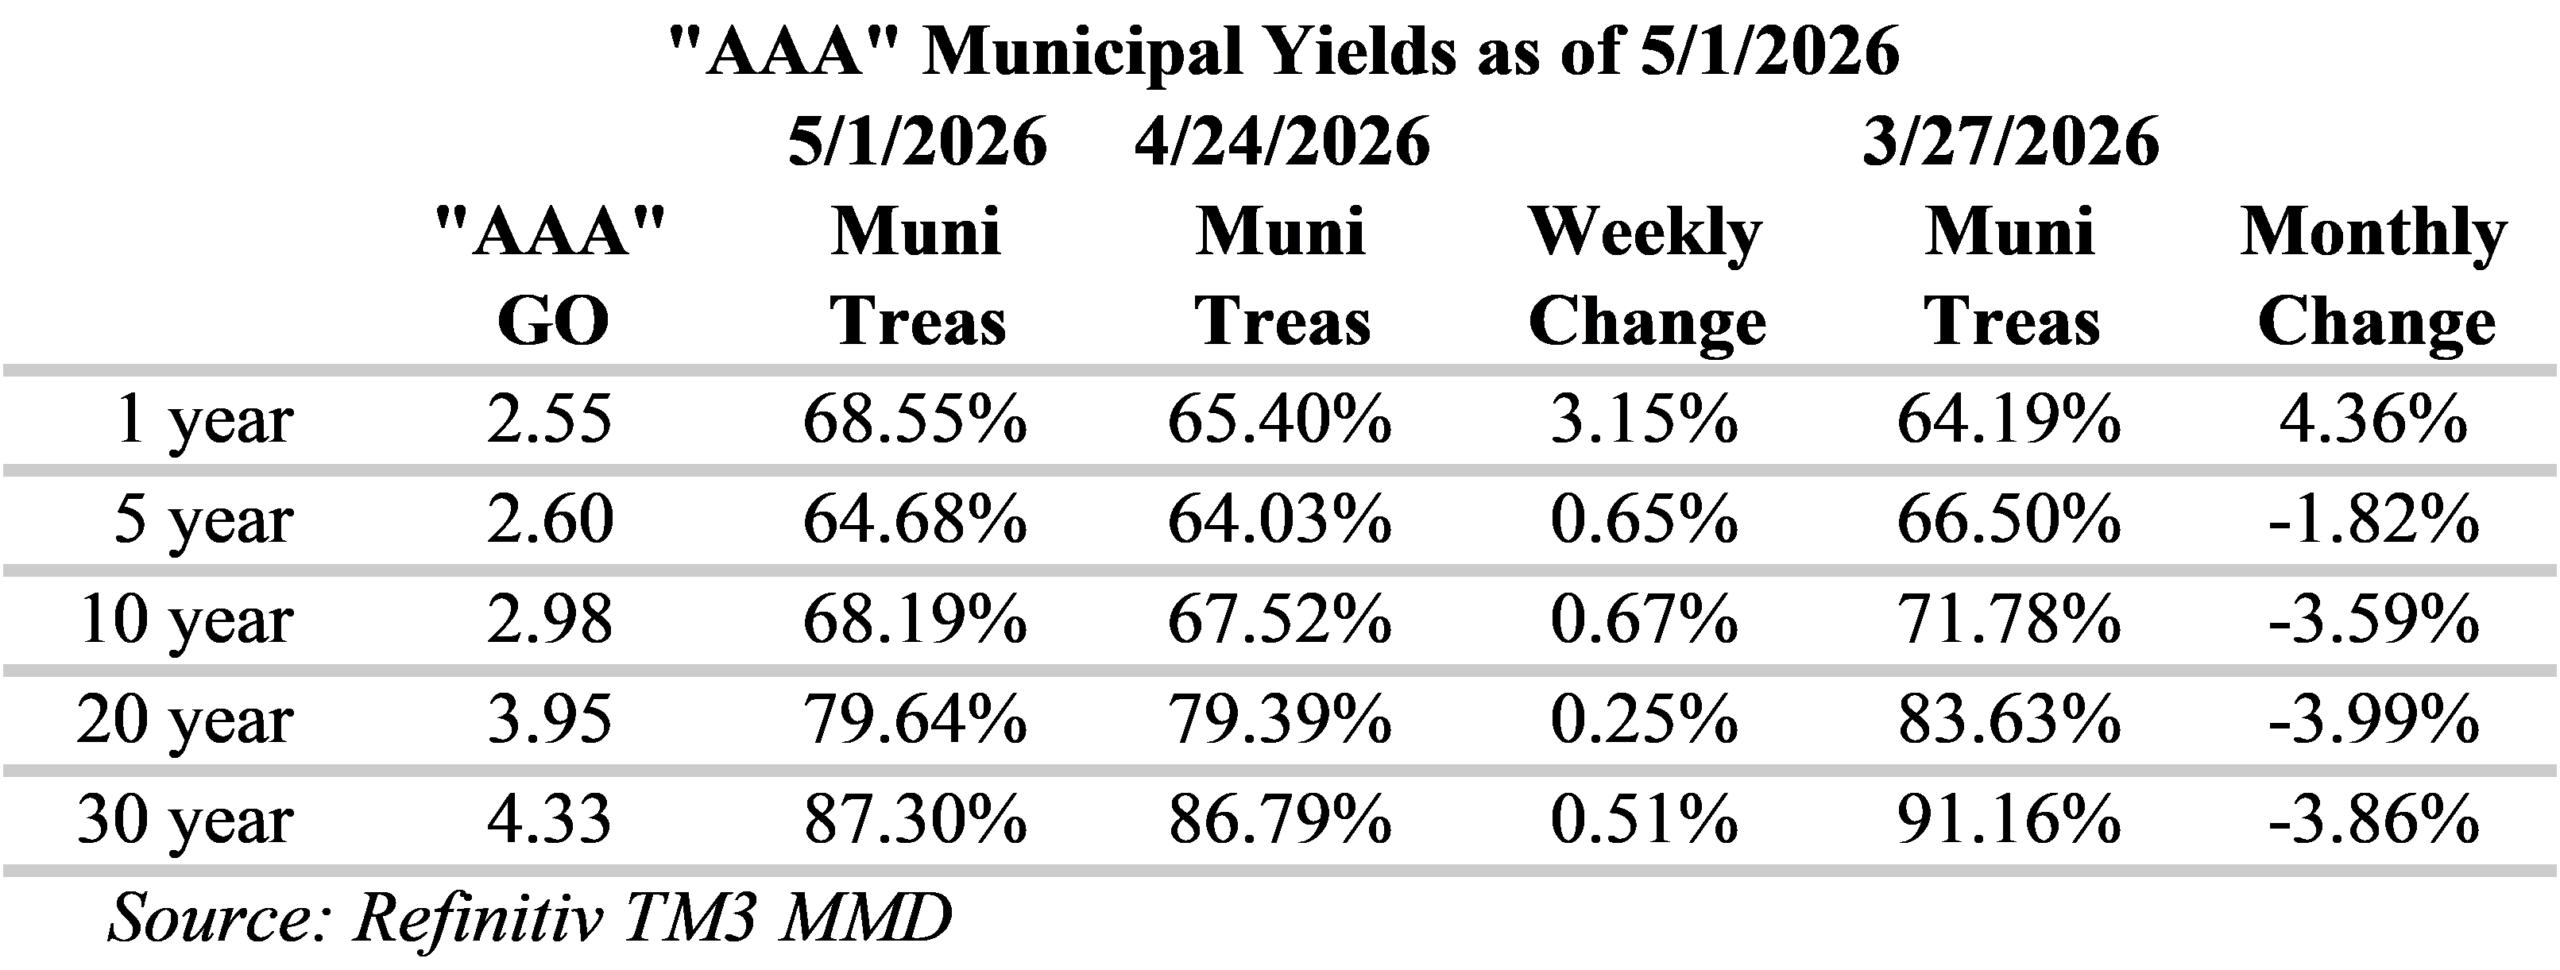
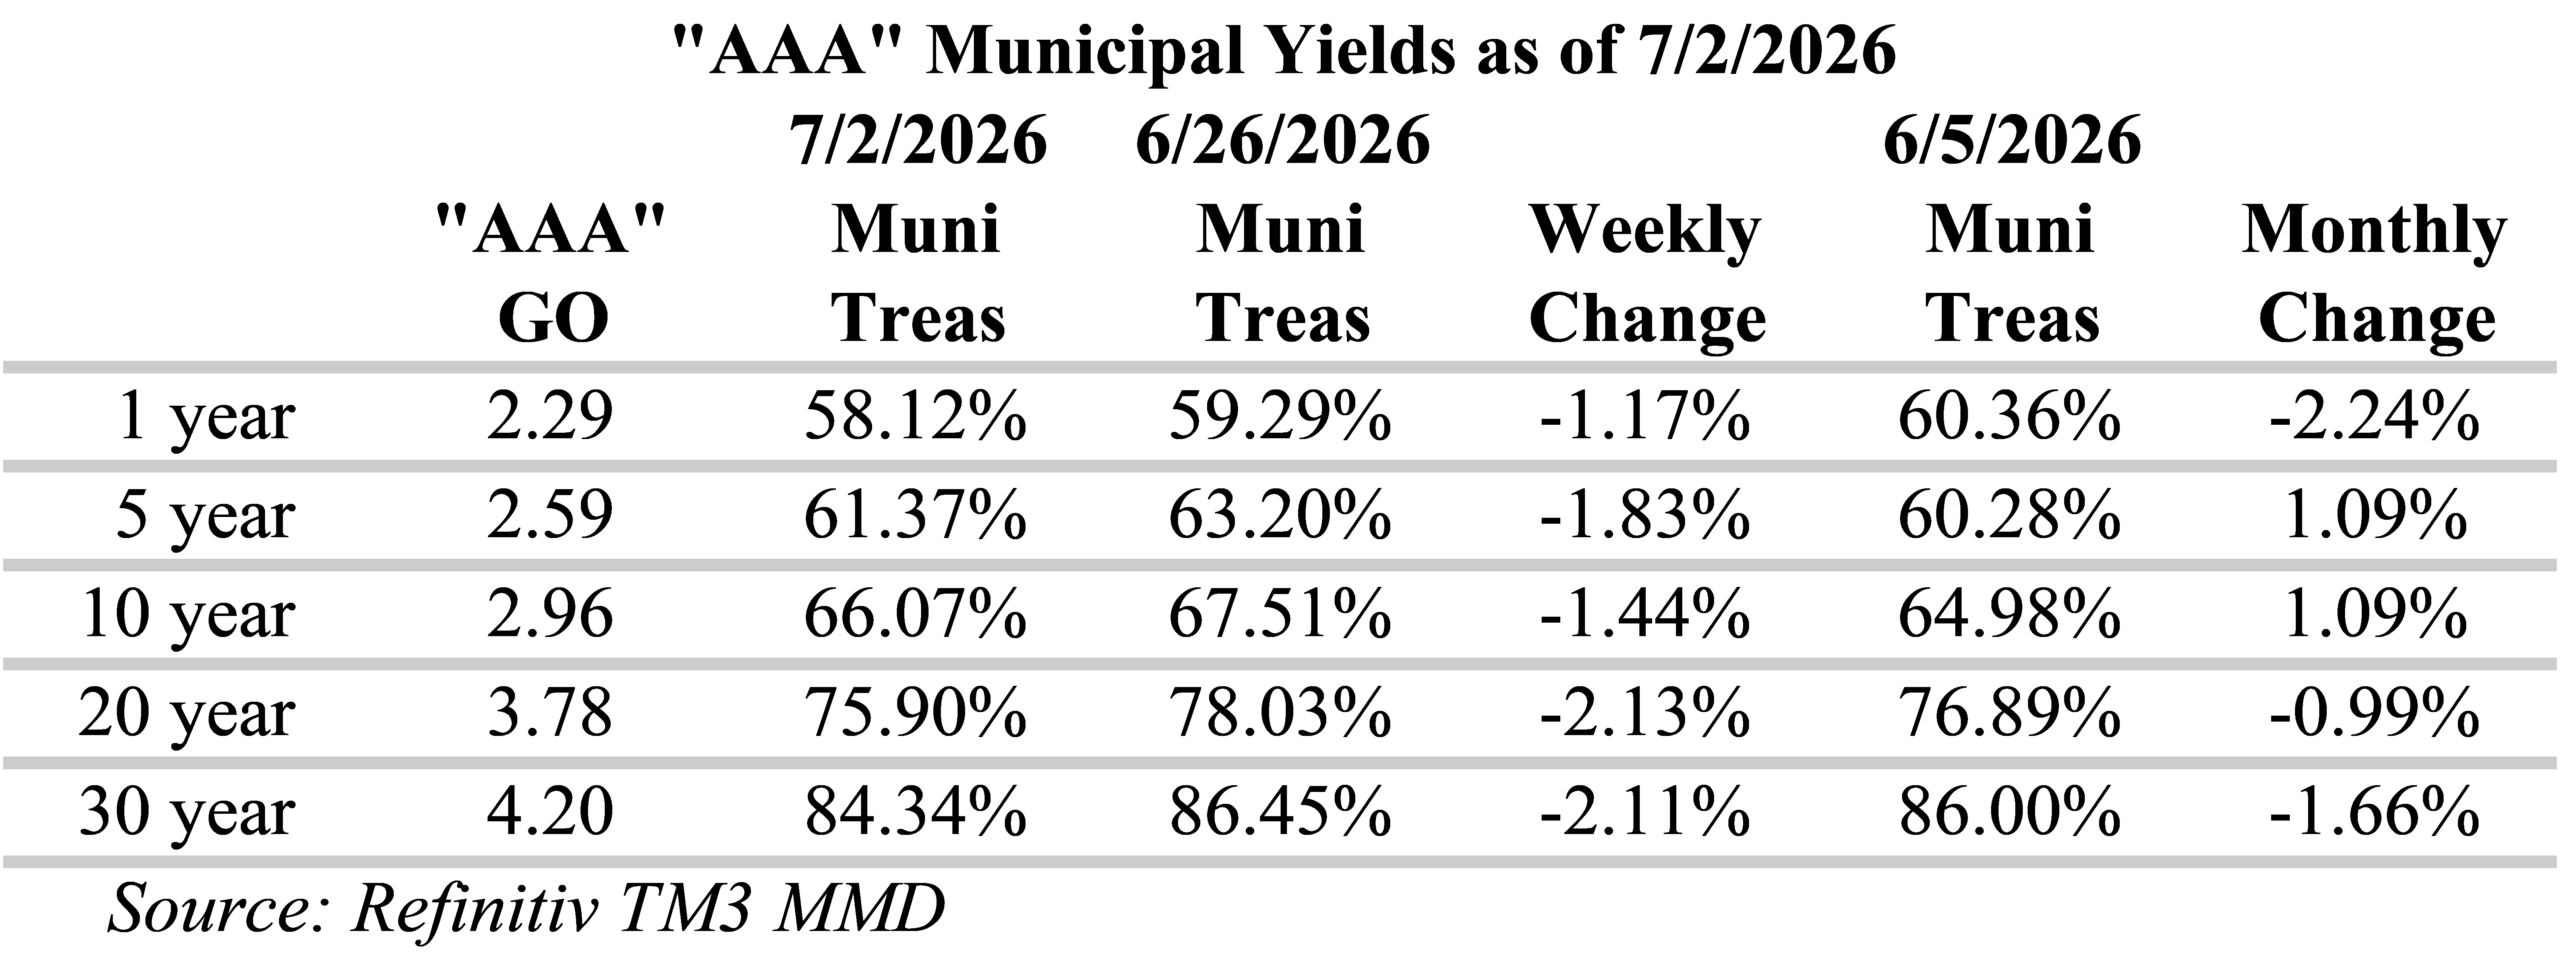
Over the past week, Municipal/Treasury ratios have generally increased (cheapened), although one-year ratios remain notably well below 60%.  In recent weeks, ratios have fallen well below several important reference points along the curve.  Ratios for 10-year municipal yields are now well under 70% of Treasuries, 20-year ratios are below 80% and 30-year ratios are below 90% of Treasuries.  However, ratios have improved across the municipal yield curve over this past week, with the largest changes occurring from five to 10 years.  For investors seeking to maximize curve positioning with relative value, the 19 to 21-year part of the municipal yield curve is attractive with slopes of 10 to 13-bps per year and yields around 80% of Treasuries.  Although ratios past 20-years are more attractive, relative to Treasuries, the yield curve is very flat over these longer tenors. 

The Municipal the new issue calendar remains elevated this week with US state and local governments expected to sell around $11.2 billion of bonds.  Notable deals include: the New York City Transitional Finance Authority with $1.5 billion, the City of San Antonio Airport has $943.9 million, and West Valley-Mission Community College District is expected to bring $497 million to the market.  Last week, municipal bond investors added approximately $1.4 billion to municipal-bond funds, according to LSEG Lipper Global Fund Flows.  Overall, investors continue to support munis, but new issue pricings remain in focus.

Herbert J. Sims & Co. Inc. is a SEC registered broker-dealer, a member of FINRA, SIPC. The information contained herein has been prepared based upon publicly available sources believed to be reliable; however, HJ Sims does not warrant its completeness or accuracy and no independent verification has been made as to its accuracy or completeness. The information contained has been prepared and is distributed solely for informational purposes and is not a solicitation or an offer to buy or sell any security or instrument or to participate in any trading or investment strategy, and is subject to change without notice. All investments include risks. Nothing in this message or report constitutes or should be construed to be accounting, tax, investment or legal advice.

Curve Commentary: July 13, 2026

Overview

The war in Iran continues to make headlines with Iran reportedly insisting that ships obtain permission and the US declaring the Strait is open to all vessels.  This uncertainty has resulted in oil continuing to price at higher levels, West Texas Intermediate is back in the mid 70’s this morning.  Inflation concerns with higher energy prices continue to move the long-end of the Treasury yield curve, with maturities past 20-years now eclipsing 5%.  On the short-end, we are experiencing upward pressure around the policy sensitive 2-year tenor amid speculation the Fed will raise rates sooner rather than later.  Fed funds futures are now almost fully pricing in a rate hike of 25bp in September (92%), which, as of last week, was previously thought to not occur until December.  This week we will be closely following the US data on CPI and producer prices as they will be the final inflation prints before the Fed’s meeting later this month.

Implied Overnight Rate & Number of Hikes/Cuts

Insights and Strategy

Treasury curves steepened a bit over the past week, while the municipal yield curve followed in sympathy.  However, the slope of the 10 to 30-year municipal curve remains near the tightest levels seen in over a year.  This flattening is the result of shifting expectation for longer maturities as markets adjust inflation expectations against the strength of the economy.  When comparing the municipal yield curve to the Treasury curve, the first 6 months immediately stand-out with the inverted shape of the municipal curve contrasting with the steeply sloped Treasury curve.  The slope at the long-end of the municipal yield curve, past 20-years, remains relatively flat with a total slope of 34 bps from 21-30-years.  Due to this flat tail, municipal bond investors can currently buy 20-year maturities that yield almost 90% of the 30-year curve versus 71% for 10-year maturities.

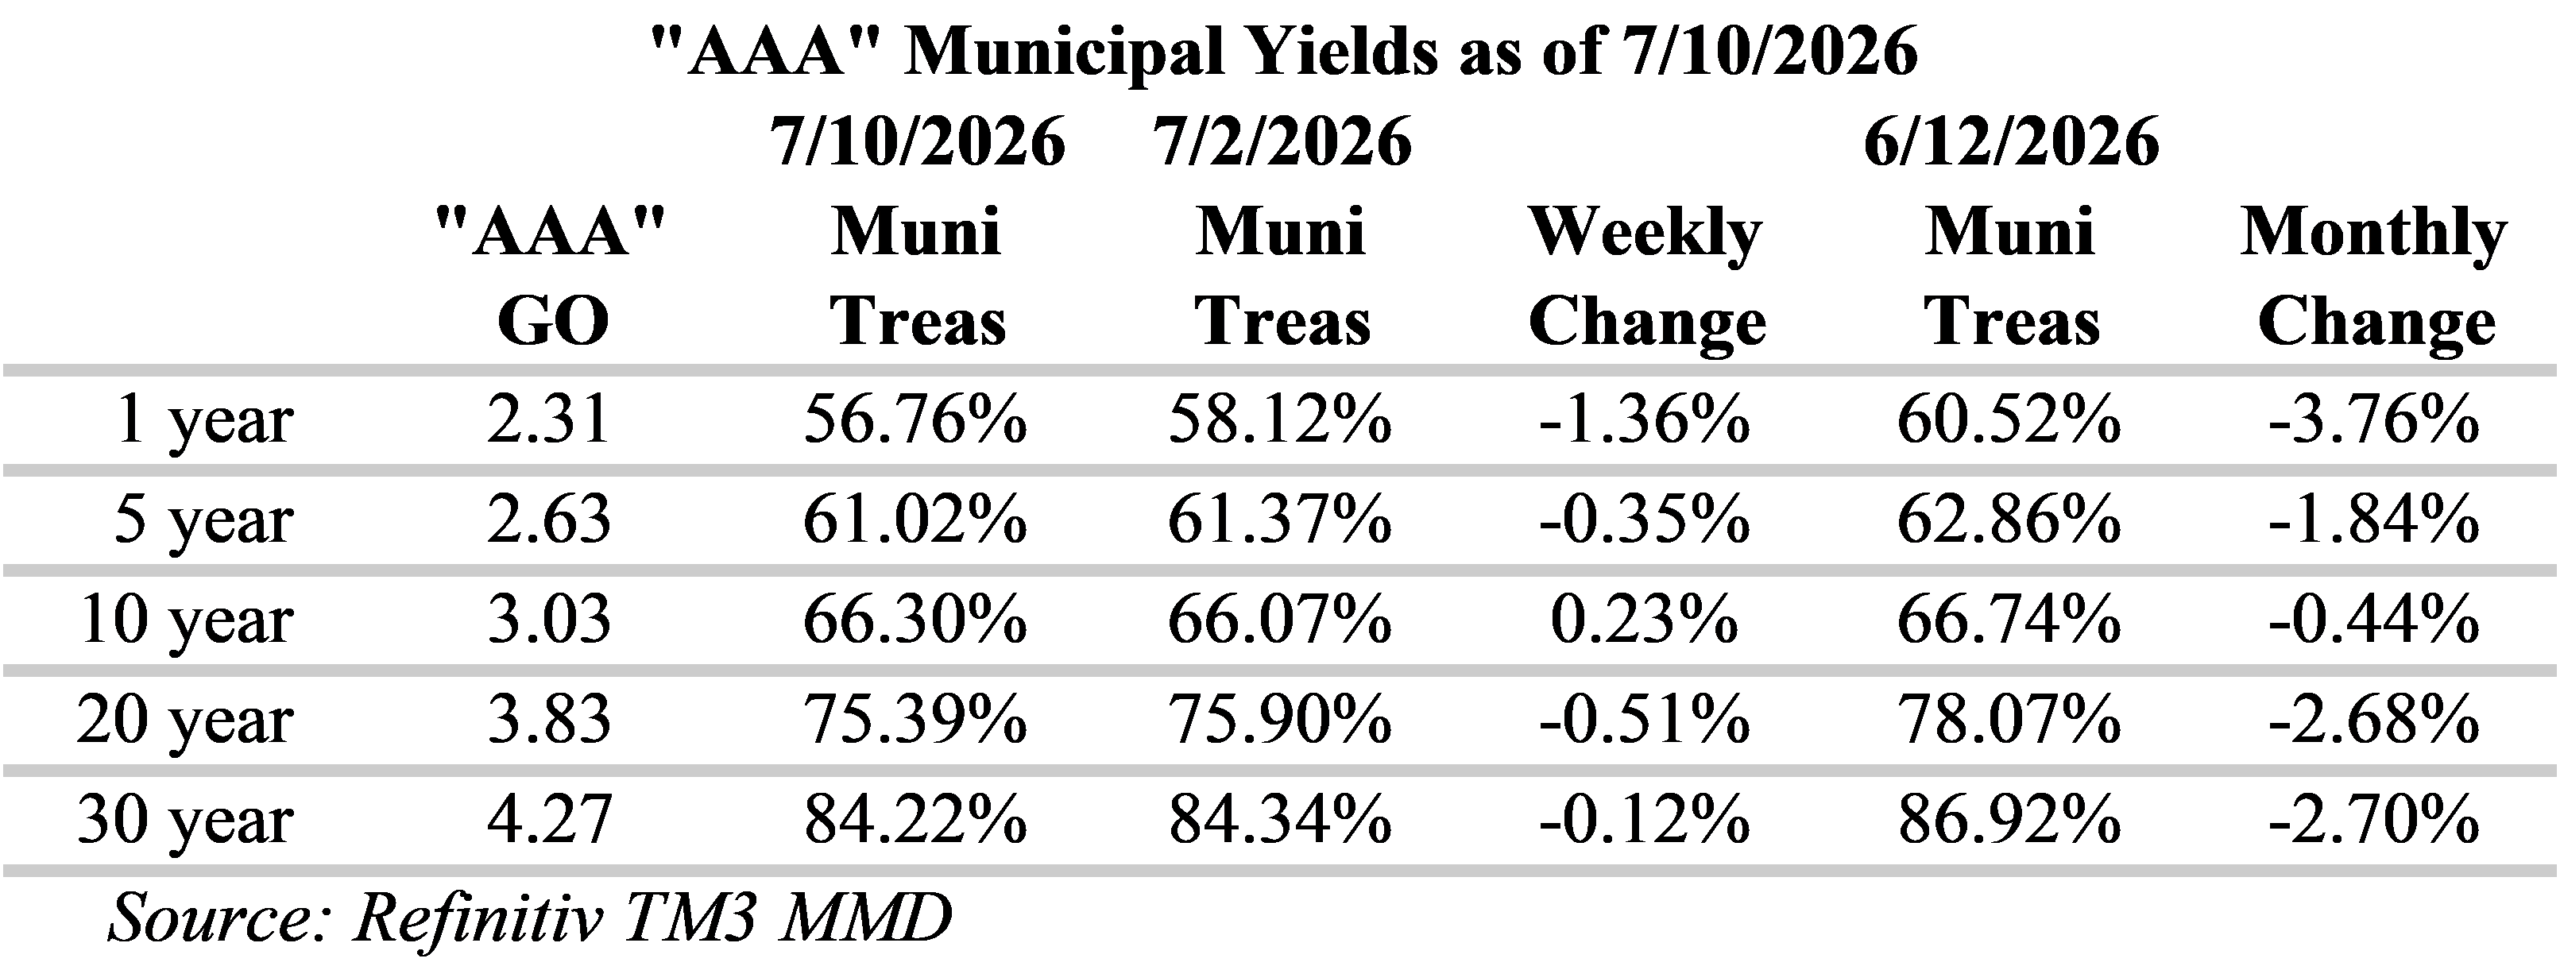
Over the past week, Municipal/Treasury ratios have generally decreased (richened), with one-year ratios notably well below 60%.  Furthermore, ratios have recently fallen well below several important reference points along the curve.  Ratios for 10-year municipal yields are now well under 70% of Treasuries, 20-year ratios are below 80% and 30-year ratios are below 90% of Treasuries.  For investors seeking to maximize curve positioning with relative value, the 19 to 21-year part of the municipal yield curve is attractive with slopes of 10 to 13-bps per year and yields around 80% of Treasuries.  Although ratios past 20-years are more attractive, relative to Treasuries, the yield curve is very flat over these longer tenors.
The Municipal the new issue calendar remains elevated this week with US state and local governments expected to sell around $12.5 billion of bonds.  Notable deals include: the New York State Thruway Authority, which plans to sell $2.44 billion; Aquarion Water Authority Water System, with $2.37 billion; New Jersey Turnpike Authority, with $1.06 billion; and, Norton Healthcare Obligated Group is expected to bring $504 million to the market.  In addition, technical conditions remain supportive of the primary market.  Last week, municipal bond investors added approximately $1.4 billion to municipal-bond funds, according to LSEG Lipper Global Fund Flows.

Herbert J. Sims & Co. Inc. is a SEC registered broker-dealer, a member of FINRA, SIPC. The information contained herein has been prepared based upon publicly available sources believed to be reliable; however, HJ Sims does not warrant its completeness or accuracy and no independent verification has been made as to its accuracy or completeness. The information contained has been prepared and is distributed solely for informational purposes and is not a solicitation or an offer to buy or sell any security or instrument or to participate in any trading or investment strategy, and is subject to change without notice. All investments include risks. Nothing in this message or report constitutes or should be construed to be accounting, tax, investment or legal advice.

Curve Commentary: July 6, 2026

Overview

The Bureau of Labor Statistics released its Employment Situation report last week that noted fewer-than-expected jobs added and a drop in the unemployment rate to 4.2%.  Recently, anxieties have been high regarding the potential for rate hikes under new Fed Chairman Kevin Warsh.  Following last week’s report, fed funds futures are now anticipating the Fed will hike rates 25bp in December which was previously thought to occur as soon as October.  Declining geopolitical tensions and oil prices combined with a more dovish outlook for the Fed could create an accommodative environment for the record issuance we have seen in the municipal market this year.

Implied Overnight Rate & Number of Hikes/Cuts

Insights and Strategy

Treasury curves steepened a bit over the past week, while the municipal yield curve is almost unchanged.  Currently, the slope of 10 to 30-year municipal curve is at the tightest levels seen in over a year.  This flattening is the result of longer maturities responding to declining inflation expectations.  When comparing the municipal yield curve to the Treasury curve, the first 6 months stand-out with the inverted shape of the municipal curve contrasting starkly with the steeply sloped Treasury curve.  Although the yield curve has flattened from 10 to 30-years, Investors continue be rewarded for extending out the yield curve with the steepest yields in the 19-21-year maturity range.  The slope at the long-end of the municipal curve, past 20-years, remains relatively flat with a total slope of 32 bps from 21-30-years.  Due to this flat tail, municipal bond investors can currently buy 20-year maturities that yield 90% of the 30-year curve versus 70% for 10-year maturities.

Municipal/Treasury ratios have generally decreased (richened), ratios are now one to two percent lower than a week ago.  Notably, one-year ratios are well below 60%.  Ratios on the long-end for 20-years and longer, are now meaningfully lower.  Municipals have recently fallen well below several important reference points along the curve.  Ratios for 10-year municipal yields are now well under 70% of Treasuries, 20-year ratios are below 80% and 30-year ratios are below 90% of Treasuries.  For investors seeking to maximize curve positioning with relative value, the 19 to 21-year part of the municipal yield curve is attractive with slopes of 10 to 13-bps per year and yields around 80% of Treasuries.  Although ratios past 20-years are more attractive, relative to Treasuries, the yield curve is very flat over these longer tenors. 

Following last week’s holiday closures, the Municipal the new issue calendar is significantly higher with US state and local governments expected to sell around $15.1 billion of bonds.  Notable deals include: Aquarion Water Authority Water System Revenue Bonds with $2.37 billion, California State University has scheduled $1.8 billion, Massachusetts Port Authority is expected to offer $812 million and Massachusetts Bay Transportation Authority Sales Tax Revenue has $767.4 million on the calendar.  In addition, technical conditions remain supportive of the primary market.  Last week, municipal bond investors added approximately $1.7 billion to municipal-bond funds, according to LSEG Lipper Global Fund Flows.

Herbert J. Sims & Co. Inc. is a SEC registered broker-dealer, a member of FINRA, SIPC. The information contained herein has been prepared based upon publicly available sources believed to be reliable; however, HJ Sims does not warrant its completeness or accuracy and no independent verification has been made as to its accuracy or completeness. The information contained has been prepared and is distributed solely for informational purposes and is not a solicitation or an offer to buy or sell any security or instrument or to participate in any trading or investment strategy, and is subject to change without notice. All investments include risks. Nothing in this message or report constitutes or should be construed to be accounting, tax, investment or legal advice.
Curve Commentary: June 29, 2026

Overview

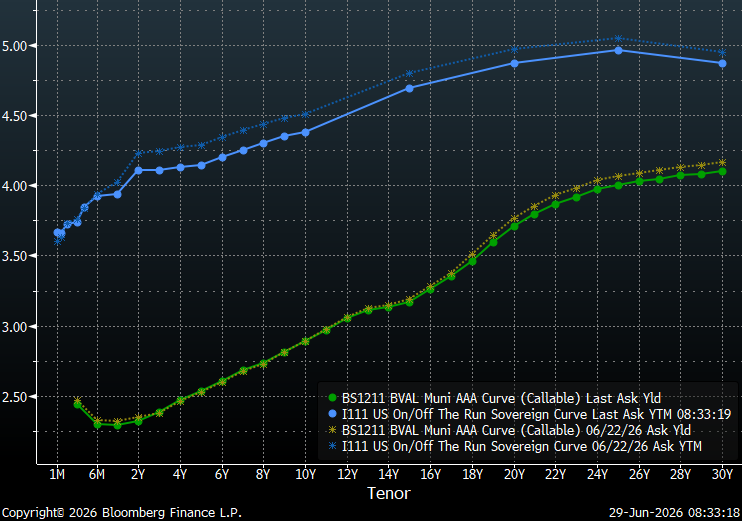
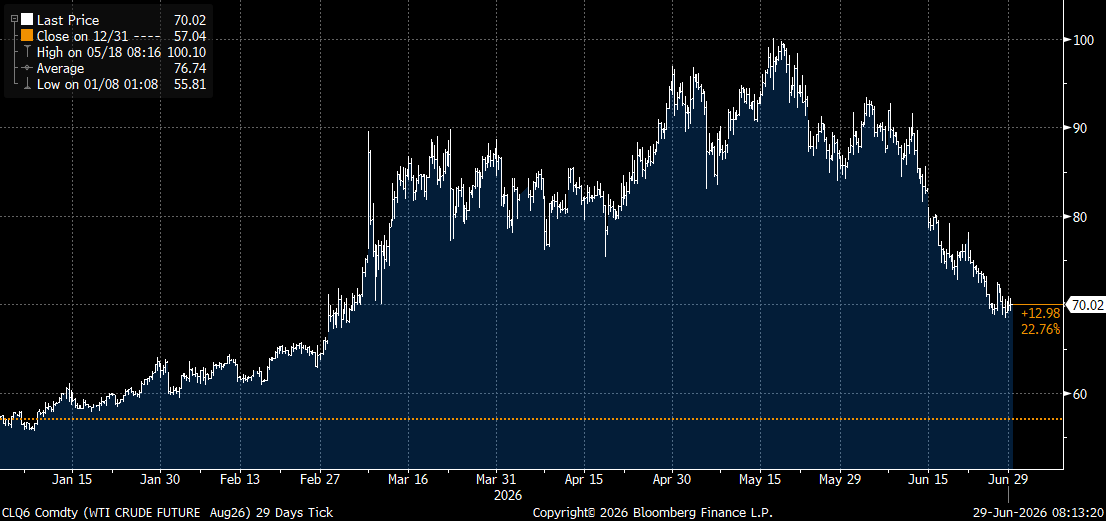
Following an escalation of tensions in the Strait of Hormuz, Iran and the US have reportedly agreed to stop mutual attacks.  Although there is an agreement in place, shipowners remain wary of crossing the strait.  As a result, oil prices are up again this morning and we are seeing Treasuries trade off a bit, particularly in the intermediate portion of the yield curve.  While this week is a holiday week with a lighter new issue calendar, accounts are likely to be attentive with over $100 billion in combined July and August redemptions.

West Texas Intermediate Crude Futures

Insights and Strategy

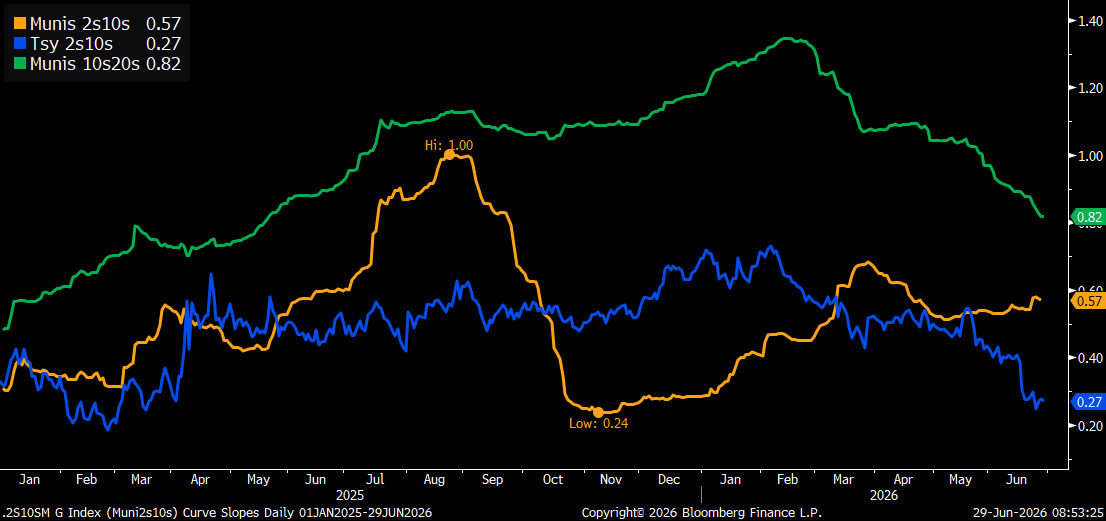
Both municipal and Treasury curves have flattened over the past week.  Currently, the slope of 2 to 10-year Treasuries is less than half of what it was in mid-May and near the tightest levels seen in over a year.  This flattening is the result of shorter-dated Treasuries anticipating rate hikes while longer maturities face inflation uncertainties.  However, the first 6 months of the curves could not be more different, with munis inverted and Treasuries steeply upwardly sloped.  Although the yield curve has flattened, Investors continue be rewarded for extending out the yield curve with the steepest yields in the 19-21-year maturity range.  The slope at the long-end of the municipal yield curve, past 20-years, remains relatively flat with a total slope of 31 bps from 21-30-years.  Due to this flat tail, municipal bond investors can currently buy 20-year maturities that yield over 90% of the 30-year curve versus 70% for 10-year maturities.

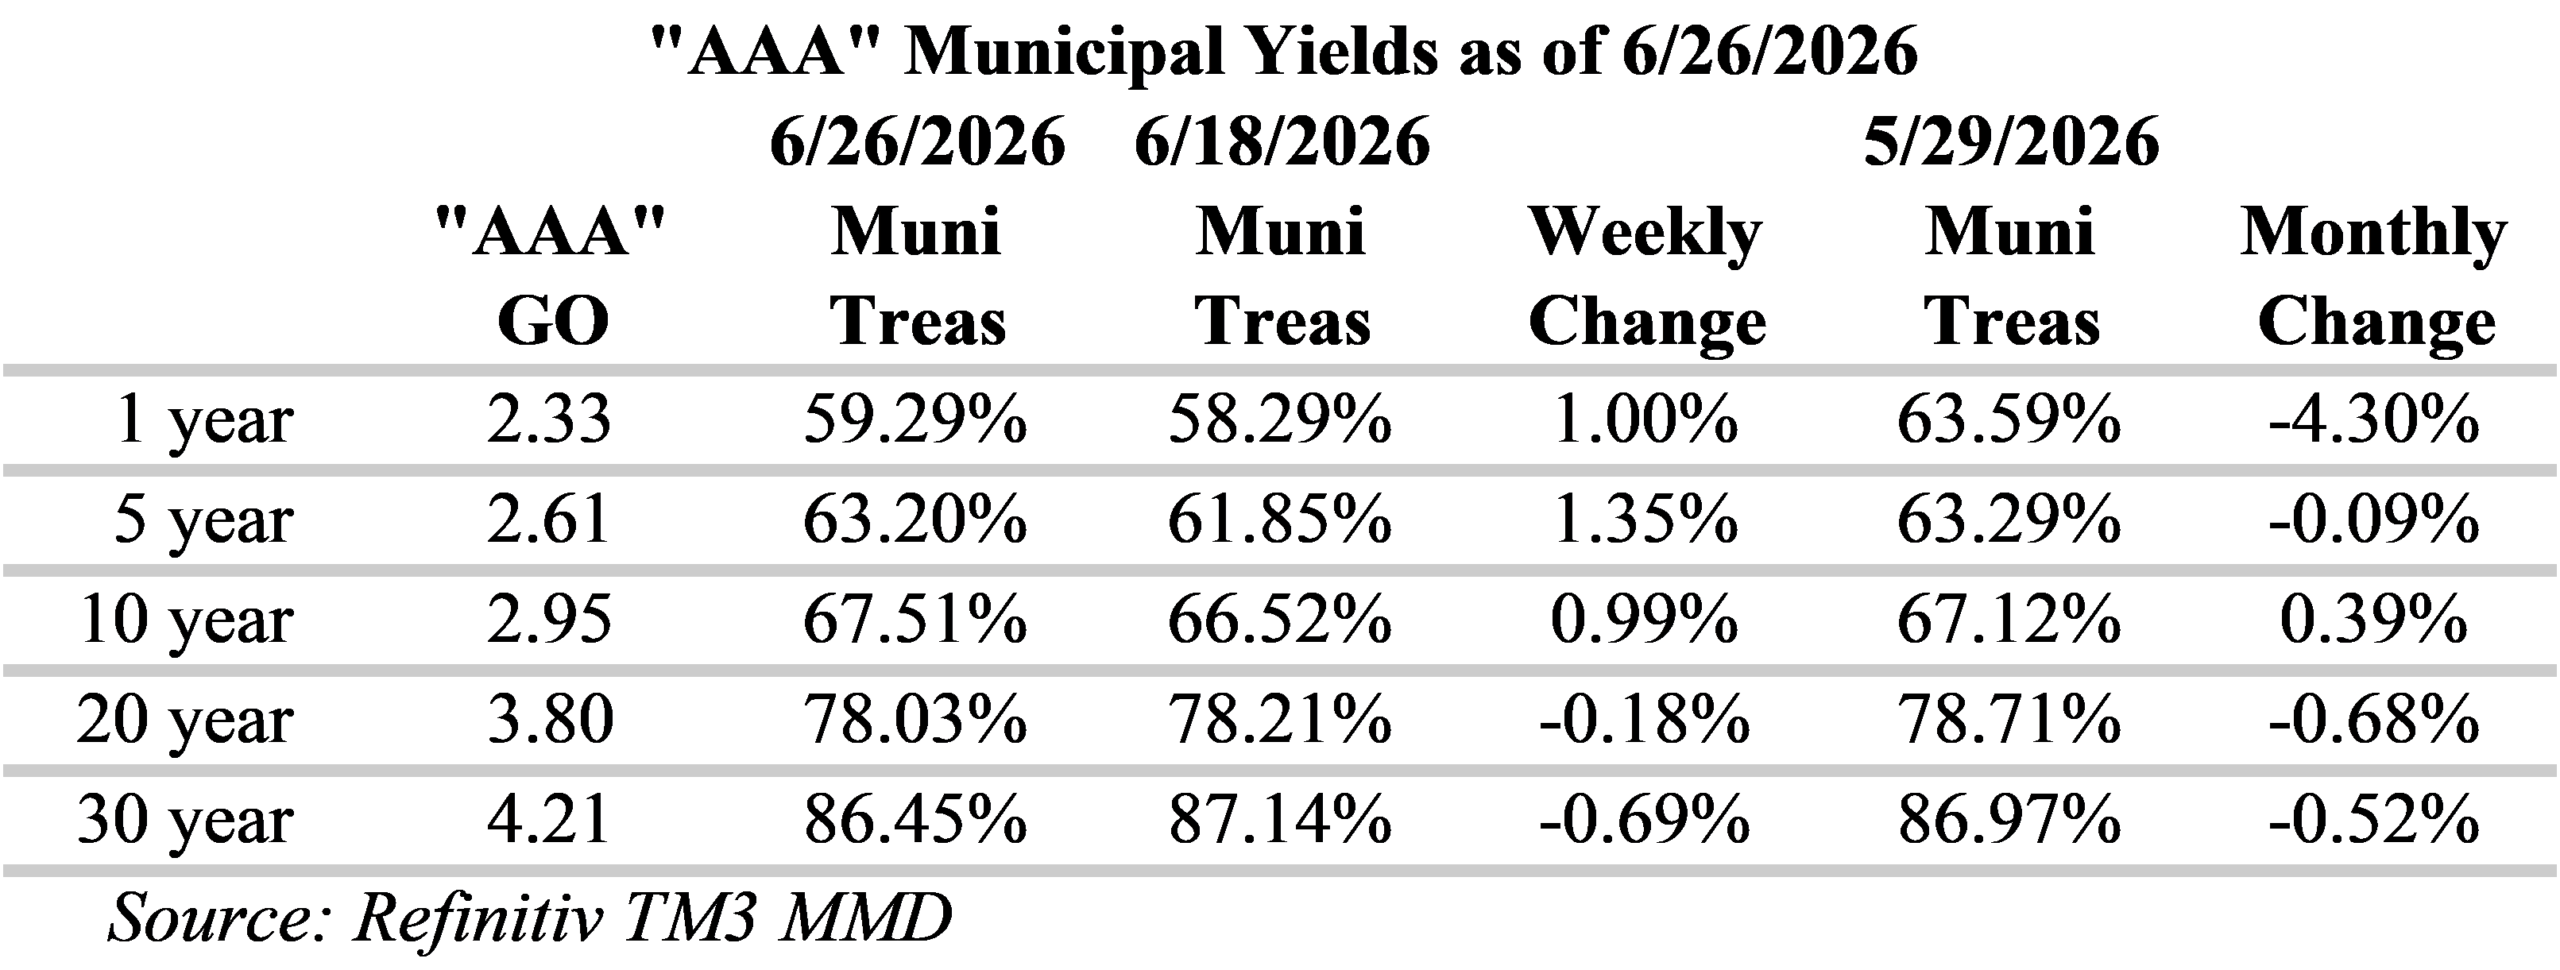
Municipal/Treasury ratios have generally increased (cheapened) for periods shorter than 10-years, with one-year ratios 1% higher, but still below 60% of Treasuries.  Ratios on the long-end, for 20-yewars and longer, are now slightly lower.  Municipals have fallen well below several important reference points along the curve.  Ratios for 10-year municipal yields are now well under 70% of Treasuries, 20-year ratios are below 80% and 30-year ratios are below 90% of Treasuries.  For investors seeking to maximize curve positioning with relative value, the 19 to 21-year part of the municipal yield curve is attractive with slopes of 10 to 13-bps per year and yields around 80% of Treasuries.  Although ratios past 20-years are more attractive, relative to Treasuries, the yield curve is very flat over these longer tenors.

Due to the holiday closure later this week, the Municipal the new issue calendar is significantly smaller with US state and local governments expected to sell around $7 billion of bonds.  Notable deals include: Black Belt Energy Gas District with $920 million, Massachusetts Port Authority is expected to bring $812 million, Main Street Energy Inc. has scheduled $585 million and City of San Diego Water has $429.9 million on the calendar.  In addition, technical conditions remain supportive of the primary market.  Last week, municipal bond investors added approximately $633 million to municipal-bond funds, according to LSEG Lipper Global Fund Flows.

Herbert J. Sims & Co. Inc. is a SEC registered broker-dealer, a member of FINRA, SIPC. The information contained herein has been prepared based upon publicly available sources believed to be reliable; however, HJ Sims does not warrant its completeness or accuracy and no independent verification has been made as to its accuracy or completeness. The information contained has been prepared and is distributed solely for informational purposes and is not a solicitation or an offer to buy or sell any security or instrument or to participate in any trading or investment strategy, and is subject to change without notice. All investments include risks. Nothing in this message or report constitutes or should be construed to be accounting, tax, investment or legal advice.
Curve Commentary: June 22, 2026

Overview

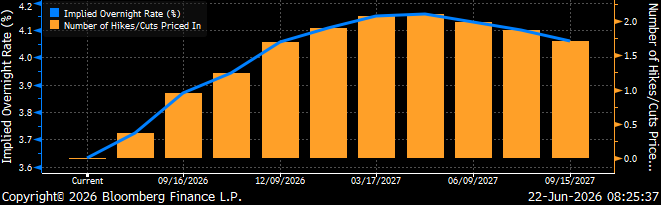
Last week the Federal Open Market Committee (FOMC) voted to hold the benchmark federal funds rate in a range of 3.5% to 3.75%, at the first gathering with Kevin Warsh as “Chairman.”  At the meeting, officials signaled growing support for rate hikes this year with half of the individual Fed members expecting to raise rates by the end of the year.  Furthermore, Warsh repeatedly reiterated the Fed’s commitment to fighting inflation.  Fed rate-hike expectations have recently shortened significantly with Fed Funds Futures pricing in two 25bp moves by March 2027.  Fed funds futures are now anticipating the Fed will hike rates 25bp as soon as October.

Implied Overnight Rate & Number of Hikes/Cuts

Insights and Strategy

The gap between two- and 10-year Treasury yields and between five- and 30-year yields has narrowed to the tightest levels in more than a year.  This flattening is the result of shorter-dated Treasuries anticipating rate hikes while longer maturities price-in a tougher inflation stance.  However, the municipal yield curve has responded in a more even fashion with an almost parallel shift downward with the first six-months remaining inverted.  Although the yield curve has flattened, Investors continue to be rewarded for extending out the yield curve, with the steepest yields in the 18-21-year maturity range.  The slope at the long-end of the municipal yield curve, past 20-years, remains relatively flat with a total slope of 31 bps from 21-30-years.  Due to this flat tail, municipal bond investors can currently buy 20-year maturities that yield almost 90% of the 30-year curve versus less than 70% for 10-year maturities.

Over the past week, municipal/Treasury ratios have generally declined for periods shorter than 10-years, with one-year ratios now well below 60%.  Ratios on the long-end, for 20-yewars and longer, are now slightly higher.  Municipals have now fallen well below several important reference points along the curve.  Ratios for 10-year municipal yields are now well under 70% of Treasuries, 20-year ratios are below 80% and 30-year ratios are below 90% of Treasuries.  For investors seeking to maximize curve positioning with relative value, the 19 to 21-year part of the municipal yield curve is attractive with slopes of 12 to 13-bps per year and yields around 80% of Treasuries.  Although ratios past 20-years are more attractive, relative to Treasuries, the yield curve is very flat over these longer tenors.

The Municipal the new issue calendar remains relatively robust this week with US state and local governments expected to sell over $12 billion of bonds.  Notable deals include: the State of Georgia with $1.57 billion, Massachusetts Bay Transportation Authority Sales Tax Revenue is scheduled to sell $767.4 million, Santa Clara Unified School District is selling $438 million and Central Florida Expressway Authority is expected to bring $430.6 million to the market.  In addition, technical conditions remain supportive of the primary market.  Last week, municipal bond investors added approximately $1.19 billion to municipal-bond funds, according to LSEG Lipper Global Fund Flows.  Furthermore, June tax-exempt reinvestment proceeds are expected to reach approximately$54.5 billion.

Herbert J. Sims & Co. Inc. is a SEC registered broker-dealer, a member of FINRA, SIPC. The information contained herein has been prepared based upon publicly available sources believed to be reliable; however, HJ Sims does not warrant its completeness or accuracy and no independent verification has been made as to its accuracy or completeness. The information contained has been prepared and is distributed solely for informational purposes and is not a solicitation or an offer to buy or sell any security or instrument or to participate in any trading or investment strategy, and is subject to change without notice. All investments include risks. Nothing in this message or report constitutes or should be construed to be accounting, tax, investment or legal advice.
Curve Commentary: June 15, 2026

Overview

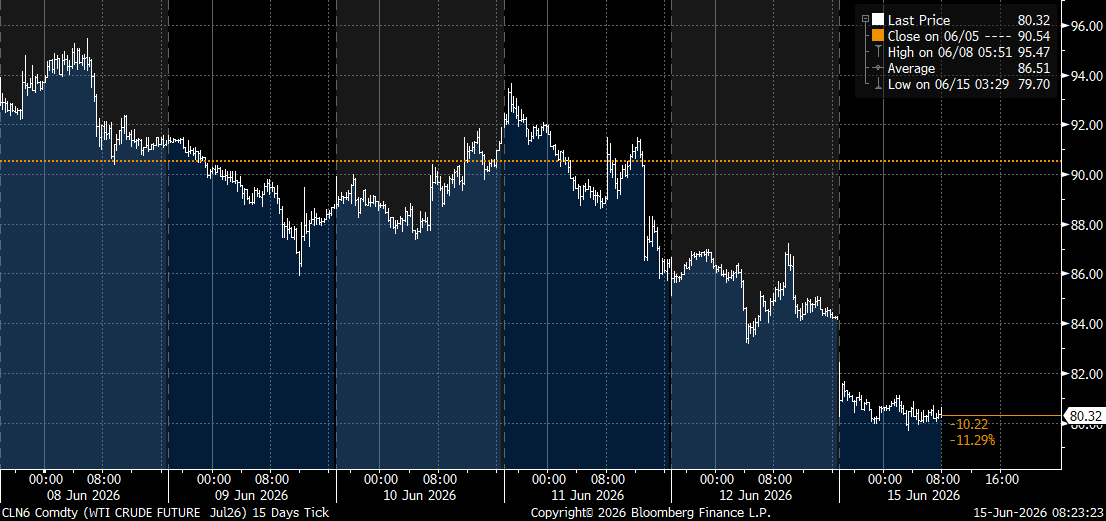
This morning oil prices slid to a three-month low on news the US and Iran reached an agreement to reopen the Strait of Hormuz.  Details of the agreement are still preliminary; but, the Strait of Hormuz is anticipated to reopen following Friday’s signing.  The agreement marks the beginning of 60 days of talks regarding Iran’s nuclear program with the potential for continued military attacks if an understanding isn’t reached.  However, with oil prices currently around $80-85 per barrel, central bankers are now under less pressure to adjust rates than last week.  As a result, Fed rate-hike expectations have shifted further into the future, with Fed Funds Futures not fully pricing in a 25bp move until March 2027.  Although the markets are not expecting the Fed to adjust rates at its meeting this week, markets will be closely following Kevin Warsh’s first Fed meeting as “Chairman.”

West Texas Intermediate Crude

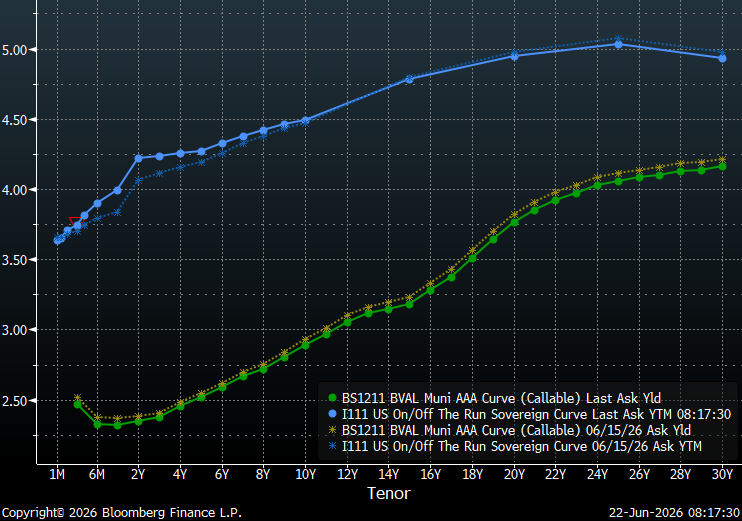
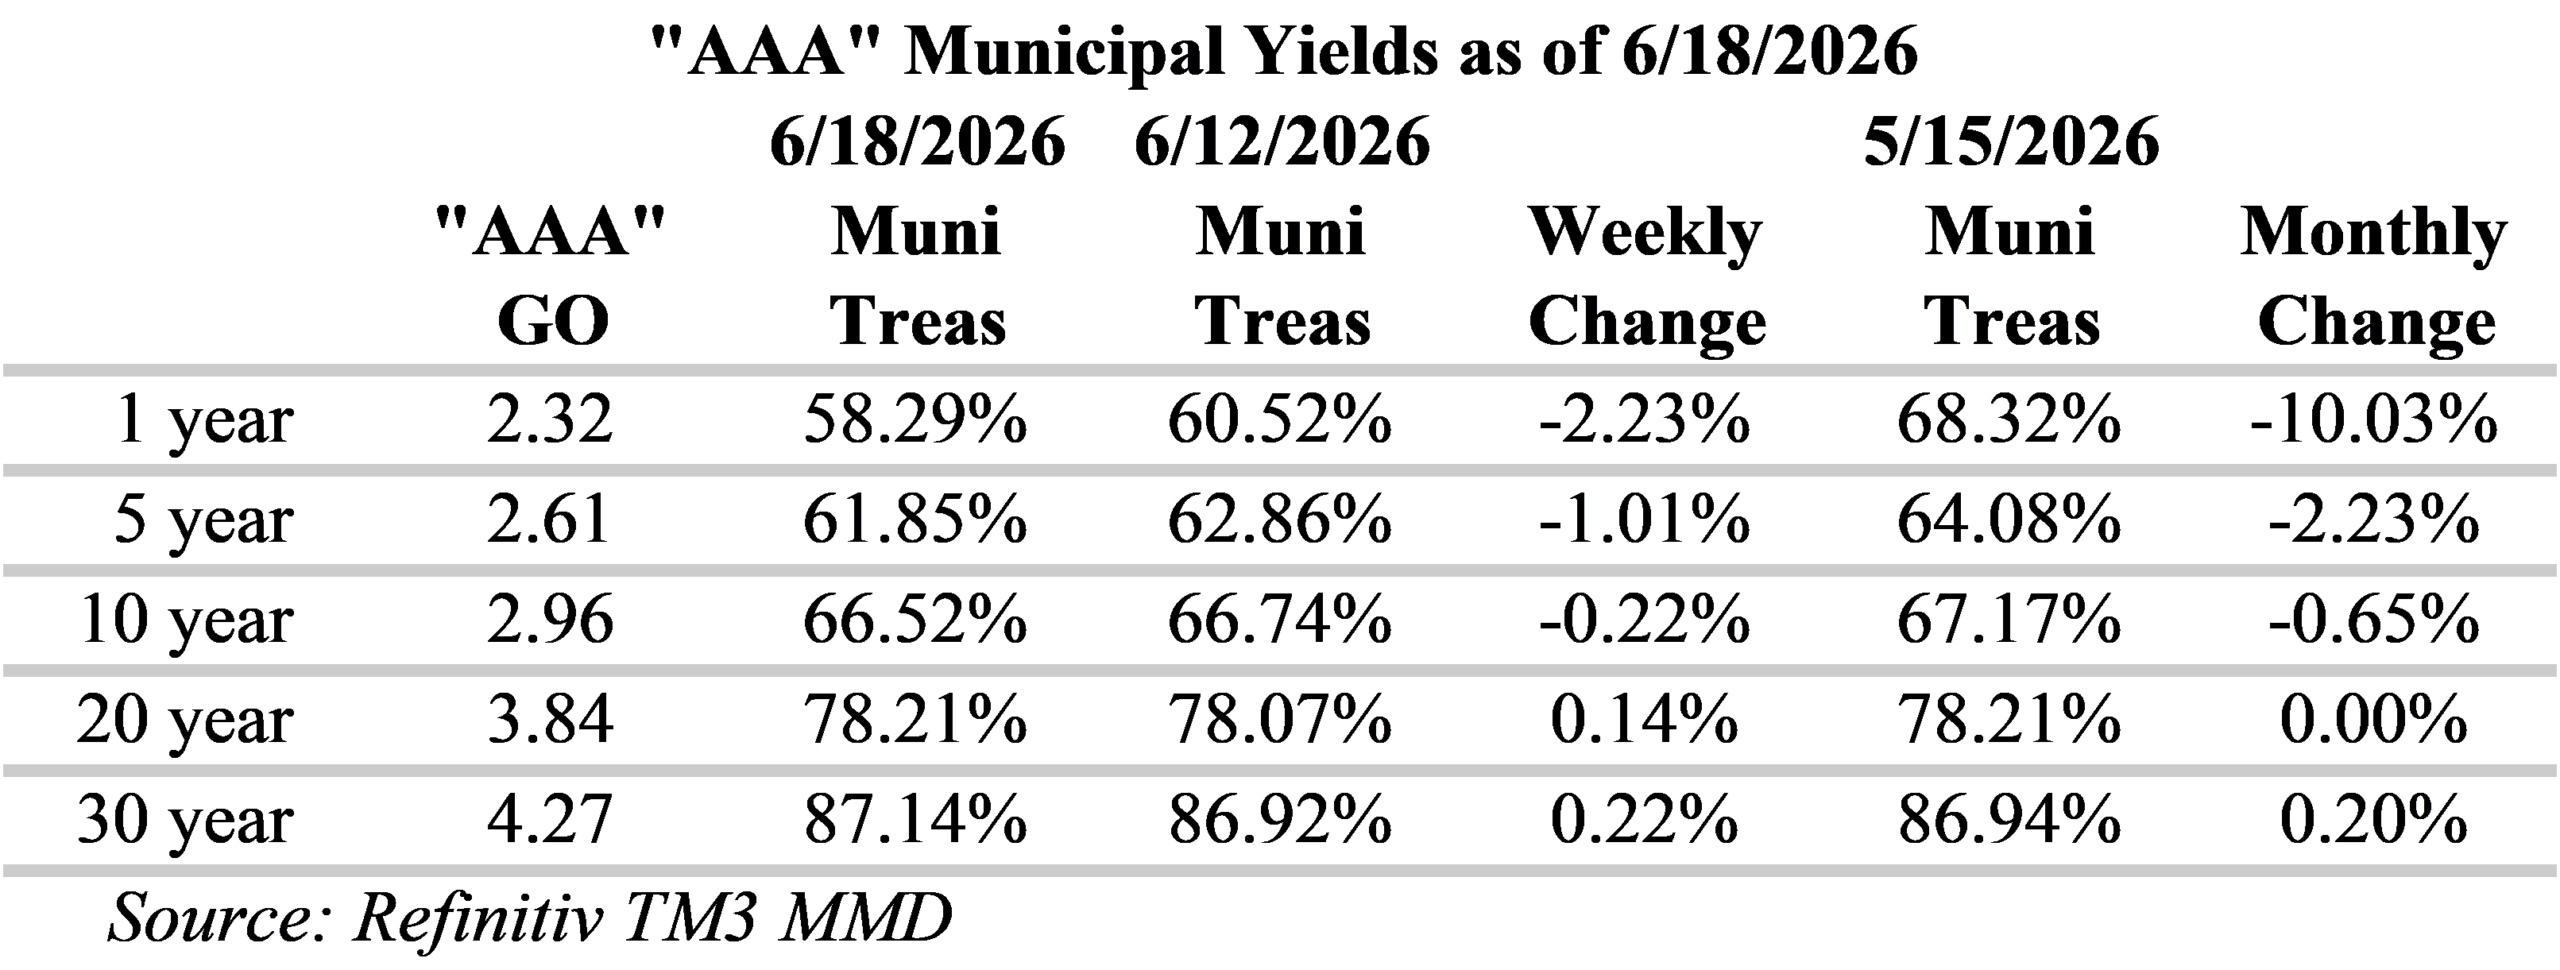
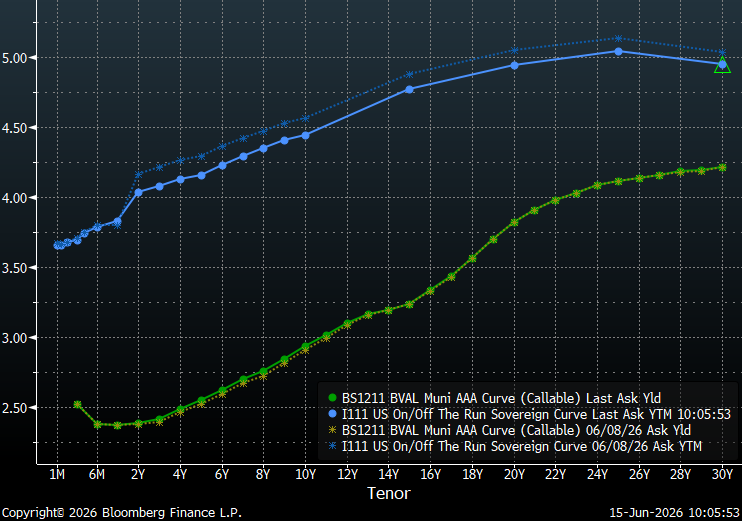
Treasuries rallied over this past week on anticipation of a deal in Iran and the opening of the Strait of Hormuz.  However, munis were little changed with yields only slightly higher from six to 14-years.  Investors continue be rewarded for extending out the yield curve with the steepest yields in the 18-21-year maturity range.  The slope at the long-end of the municipal yield curve, past 20-years, remains relatively flat with a total slope of 32 bps from 21-30-years.  Due to this flat tail, municipal bond investors can currently buy 20-year maturities that yield almost 90% of the 30-year curve versus less than 70% for 10-year maturities.

Insights and Strategy

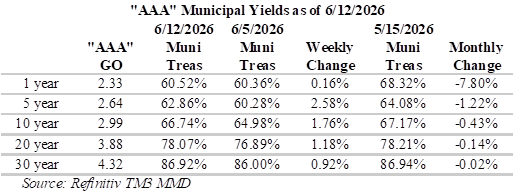
Due to the relative underperformance of munis over the past week, Municipal/Treasury ratios have generally increased over the past week.  Looking back a bit, ratios shorter than 10-years, particularly those under one-year, have become dramatically richer over the past month with one-year and shorter ratios now 7.8% lower.   Municipal bonds have now fallen well below several important reference points along the curve: ratios for 10-year municipal yields are now well under 70% of Treasuries; 20-year ratios are below 80%; and, 30-year ratios are below 90% of Treasuries.  For investors seeking to maximize curve positioning with relative value, the 19 to 21-year part of the municipal yield curve is attractive with slopes of 12 to 13-bps per year and yields around 80% of Treasuries.  Although ratios past 20-years are more attractive, relative to Treasuries, the yield curve is very flat over these longer tenors.

Despite the abbreviated holiday week, the Municipal the new issue calendar remains relatively robust this week with US state and local governments expected to sell over $11 billion of bonds.  Notable deals include: the State of Washington with $1.52 billion; County of Miami-Dade FL Aviation Revenue has scheduled $637.9 million, New York State Housing Finance Agency is estimated to offer $509.6 million, and the State of Louisiana is expected to bring $375 million to the market.  However, technical conditions remain supportive of the primary market.  Last week, municipal bond investors added approximately $625 million to municipal-bond funds, according to LSEG Lipper Global Fund Flows.  Furthermore, June tax-exempt reinvestment proceeds are expected to reach approximately$54.5 billion.

Herbert J. Sims & Co. Inc. is a SEC registered broker-dealer, a member of FINRA, SIPC. The information contained herein has been prepared based upon publicly available sources believed to be reliable; however, HJ Sims does not warrant its completeness or accuracy and no independent verification has been made as to its accuracy or completeness. The information contained has been prepared and is distributed solely for informational purposes and is not a solicitation or an offer to buy or sell any security or instrument or to participate in any trading or investment strategy, and is subject to change without notice. All investments include risks. Nothing in this message or report constitutes or should be construed to be accounting, tax, investment or legal advice.
Curve Commentary: June 1, 2026

Overview

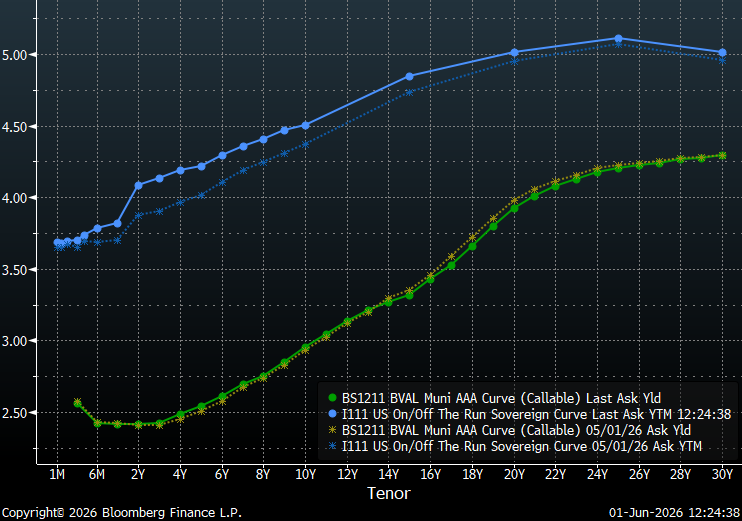
Inflation is showing signs of heating-up as the first inflation report under new Federal Reserve chief Kevin Warsh was released last week showing April consumer prices reached their highest level in almost three years.  The personal consumption expenditures price index ticked-up to 3.8% for the 12-month period ended in April, almost double the Fed’s 2% target.  However, this was not unexpected, as economists surveyed by Dow Jones forecasted a 3.8% rate.  In the Treasury Market, inflation expectations have increased anticipation the Fed will hike rates, resulting in the gap between five-year and 30-year yields narrowing to the skinniest levels seen in more than a year.  As a result, we have seen short and intermediate Treasuries underperform over the past month.  However, fund flows in the muni market remain robust, with investors adding approximately $2.3 billion last week, according to LSEG Lipper Global Fund Flows.  As a result, munis have held their ground better than Treasuries over the past month.

Insights and Strategy

Investors continue to be incentivized to extend out the yield curve with the steepest yield slopes in the 18-21-year maturity range and an overall slope of 49 bps.  However, slopes at the long-end of the municipal yield curve remain very flat with only 30 bps of slope from 21 to 30 years.  Due to this flat tail, municipal bond investors can currently buy 20-year maturities that yield over 90% of the 30-year curve versus less than 70% for 10-year maturities.

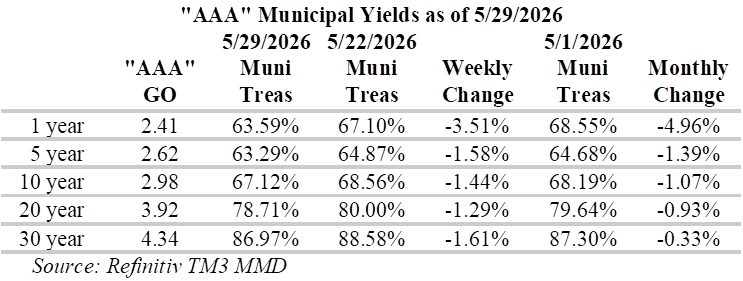
Due to the outperformance of munis, Municipal/Treasury ratios have generally declined over the past week.  Municipal bonds have continued to price at richer levels as ratios fall well below several important reference points along the curve.  Ratios for 10-year municipal yields are now under 70% of Treasuries, 20-year ratios are below 80% and 30-year ratios are below 90% of Treasuries.  For investors seeking to maximize curve positioning with relative value, the 19 to 21-year part of the municipal yield curve is attractive with slopes of 11 to 13-bps per year and yields around 80% of Treasuries.  Although ratios past 20-years are more attractive, relative to Treasuries, the yield curve is very flat over these longer tenors.

Herbert J. Sims & Co. Inc. is a SEC registered broker-dealer, a member of FINRA, SIPC. The information contained herein has been prepared based upon publicly available sources believed to be reliable; however, HJ Sims does not warrant its completeness or accuracy and no independent verification has been made as to its accuracy or completeness. The information contained has been prepared and is distributed solely for informational purposes and is not a solicitation or an offer to buy or sell any security or instrument or to participate in any trading or investment strategy, and is subject to change without notice. All investments include risks. Nothing in this message or report constitutes or should be construed to be accounting, tax, investment or legal advice.
Curve Commentary: May 18, 2026

Overview

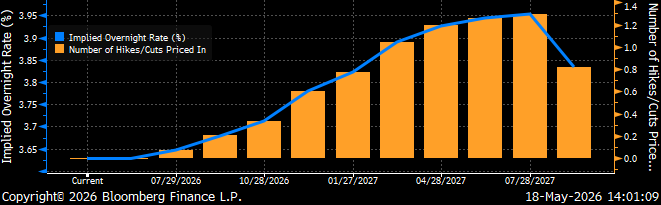
Last week, there was a global selloff in government bonds as markets recalibrated inflation risk amid surging energy prices and speculation that central banks will tighten monetary policy.  The Bureau of Labor Statistics (BLS) released its CPI report last Tuesday, which indicated that prices rose 0.6% from March and 3.8% from a year earlier.  This is the highest annual reading since May 2023 and significantly above the 0.3% and 2.7% that economists had forecast.  To compound matters, on Wednesday, the BLS released its Producer Price Index which showed prices climbing 6% year-over-year in April.  The resulting selloff was propelled by climbing crude oil prices and a US-Chinese summit that delivered only modest results and no breakthroughs on the war in Iran.  Not surprisingly, the sentiment in the Fed funds futures market has fluctuated dramatically over the past month from the Fed cutting rates to the Fed now hiking rates as soon as next March.

Insights and Strategy

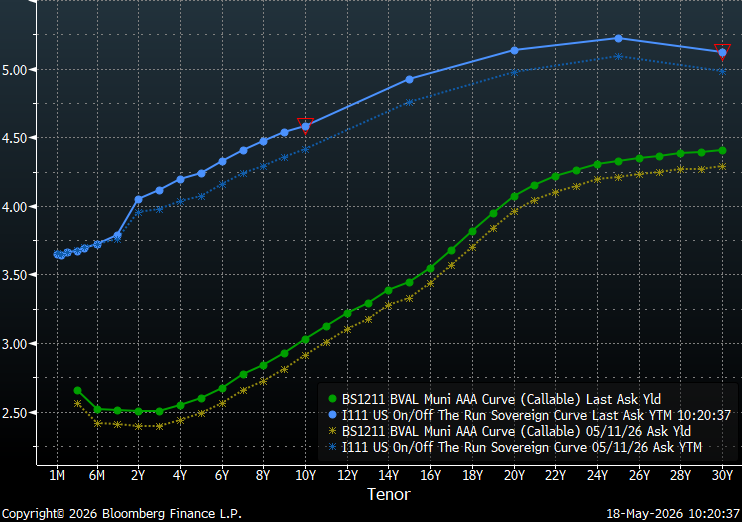
The selloff over this past week included both munis and Treasuries with Treasuries little changed for tenors under 2-years and 18-20 bps higher from five to ten years declining to 15 bps higher at 30-years.  Munis generally lagged behind Treasuries with a more uniform parallel shift upward by about ten bps across the yield curve.  Despite these developments, investors continue to be rewarded for extending out the yield curve with the steepest yields in the 18-21-year maturity range.  The slope at the long-end of the municipal yield curve has increased past 20-years, but remains relatively flat with a total slope of 32 bps from 21-30-years.  Due to this flat tail, municipal bond investors can currently buy 20-year maturities that yield over 90% of the 30-year curve versus less than 70% for 10-year maturities.

Although municipal/Treasury ratios generally declined over the past week, the short-end of the yield curve actually increased due to the muted response from Treasuries in this part of the curve.  Municipal bond ratios have now fallen just below several important reference points along the curve.  Ratios for 10-year municipal yields are under 70% of Treasuries, 20-year ratios are below 80% and 30-year ratios are below 90% of Treasuries.  For investors seeking to maximize curve positioning with relative value, the 19 to 21-year part of the municipal yield curve is attractive with slopes of 12 to 13-bps per year and yields around 80% of Treasuries.  Although ratios past 20-years are more attractive, relative to Treasuries, the yield curve is very flat over these longer tenors and investors are not being appropriately compensated to take the additional risk.

The municipal new issue calendar continues to be heavy this week with US state and local governments expected to sell over $11 billion of bonds.  Notable deals include: the School District of Philadelphia, which plans to sell $797.5 million; Great Lakes Water Authority Water Supply System Revenue is expected to sell $754 million; Missouri Highway & Transportation Commission is on the calendar with $609 million; and, Massachusetts Educational Financing Authority is expected to bring $388.4 million to market.  Despite record issuance this year, technical conditions remain supportive of the primary market.  Last week, municipal bond investors added approximately $1.3 billion to municipal-bond funds, according to LSEG Lipper Global Fund Flows.  Furthermore, May tax-exempt reinvestment proceeds are expected to reach approximately $34.5 billion.

Herbert J. Sims & Co. Inc. is a SEC registered broker-dealer, a member of FINRA, SIPC. The information contained herein has been prepared based upon publicly available sources believed to be reliable; however, HJ Sims does not warrant its completeness or accuracy and no independent verification has been made as to its accuracy or completeness. The information contained has been prepared and is distributed solely for informational purposes and is not a solicitation or an offer to buy or sell any security or instrument or to participate in any trading or investment strategy, and is subject to change without notice. All investments include risks. Nothing in this message or report constitutes or should be construed to be accounting, tax, investment or legal advice.
Curve Commentary: May 11, 2026

Overview

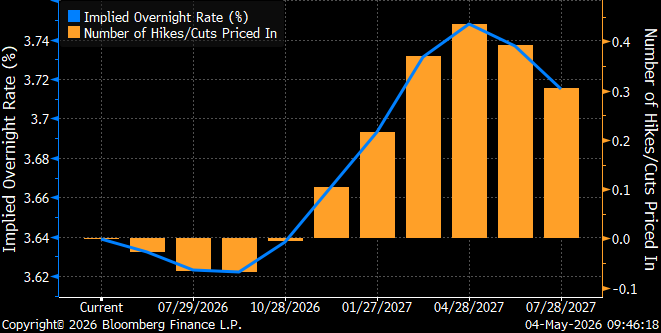
The Bureau of Labor Statistics released its Employment Situation report last Friday which reported nonfarm payroll increased by 115,000 jobs in April, despite rising energy costs from the Iran war.  This is significant as the markets contemplate the future rate path of the Fed and its dual mandate to promote both maximum employment and stable prices.  Collectively, the job gains in March and April mark the strongest two-month increase since 2024.  Recent employment data gives the Fed justification to maintain interest rates at current levels, for the foreseeable future, while they focus on inflationary risks from rising energy prices.

Insights and Strategy

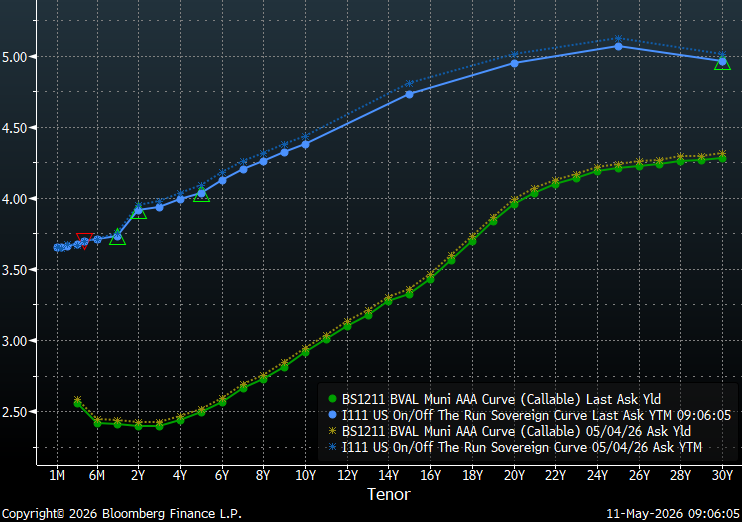
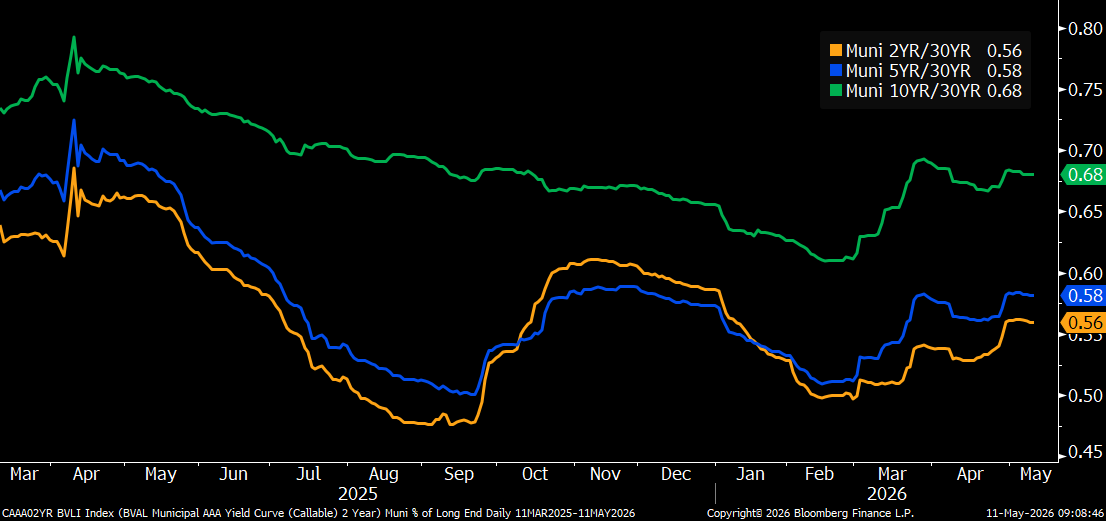
Over the past week, both munis and Treasuries advanced with a modest decrease of four and a half to seven and a half basis points in Treasury yields for all but the shortest maturities.  Munis lagged with a more uniform response over the week with a parallel shift downward of about three basis points.  The biggest changes in Treasuries occurred in the 15 to 20-year tenor where rates fell by about seven basis points.  Despite these developments, investors continue be rewarded for extending out the yield curve with the steepest yields in the 18-21-year maturity range.  The muni yield curve has generally flattened over the past 3-months with short yields rising faster than longer maturities as the narrative for rate cuts and inflation has shifted.  As a result, the percentage of yields relative to the 30-year curve has increased for shorter maturities.  The long-end of the yield curve remains increasingly flat past 20-years, with a total slope of 26 bps from 21-30-years.  Due to this flat tail, municipal bond investors can currently buy 20-year maturities that yield over 90% of the 30-year curve versus less than 70% for 10-year maturities.

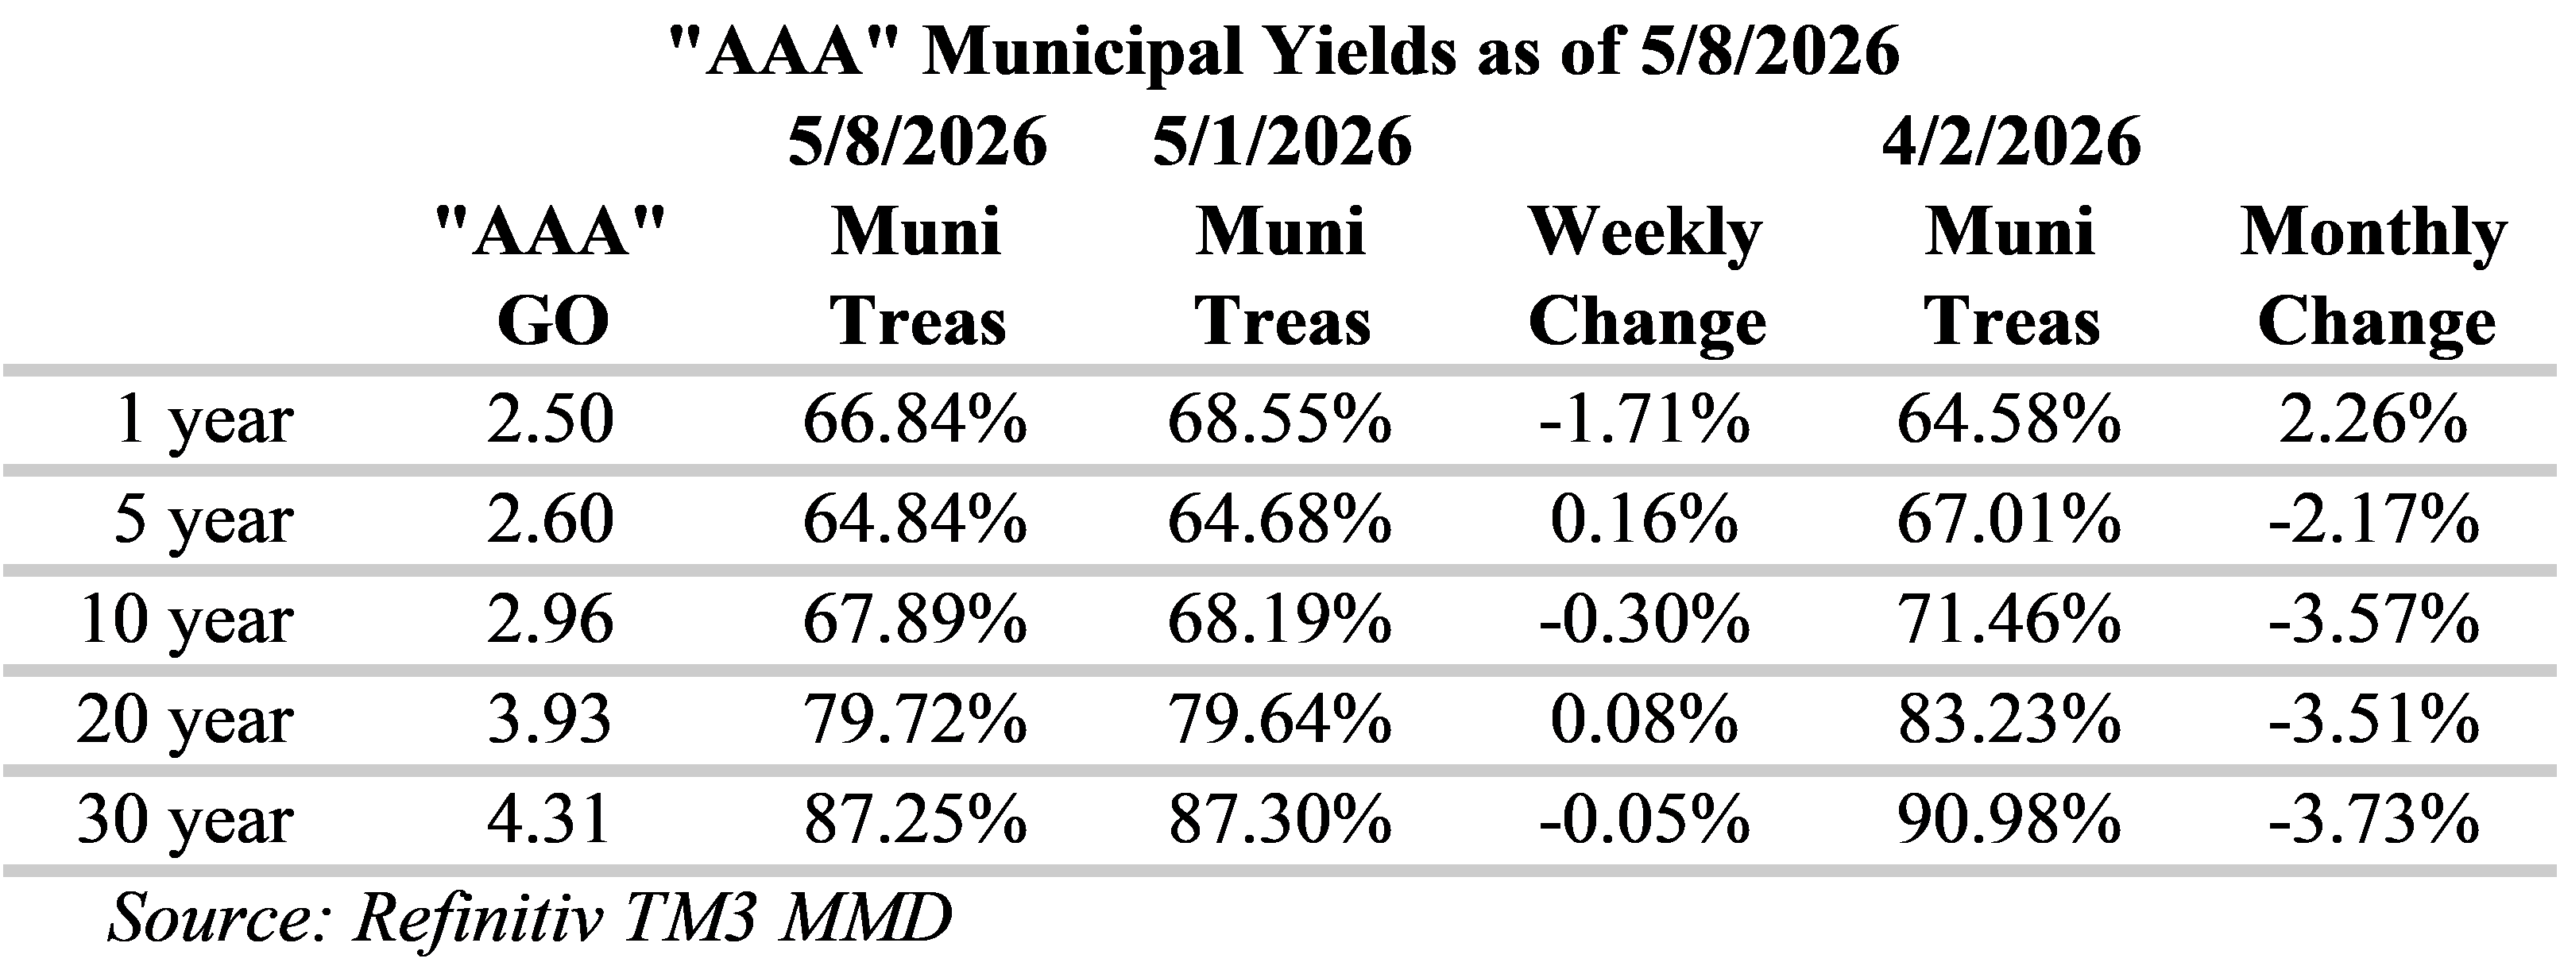
Municipal/Treasury ratios have generally declined over the past week as the short-end of the yield curve declined more than the long-end.  Municipal bonds have fallen just below several important reference points along the curve.  Ratios for 10-year municipal yields are under 70% of Treasuries, 20-year ratios are below 80% and 30-year ratios are below 90% of Treasuries.  For investors seeking to maximize curve positioning with relative value, the 18 to 21-year part of the municipal yield curve is attractive with slopes of 12 to 13-bps per year and yields approaching 80% of Treasuries.  Although ratios past 20-years are more attractively priced, relative to Treasuries, the yield curve is very flat over these longer tenors.

The Municipal new issue calendar picks-up again this week as US state and local governments are expected to sell over $13 billion of bonds.  Notable deals include: the State of Connecticut, which plans to sell $1.12 billion of bonds; the City of Atlanta Water & Wastewater Revenue has scheduled $1.1 billion; the City of Boston is expected to offer $609.3 million; and, Trustees of Columbia University in the City of New York is scheduled to bring $486.9 million to the market.  Despite record issuance this year, technical conditions remain supportive of the primary market.  Last week, municipal bond investors added approximately $1.8 billion to municipal-bond funds, according to LSEG Lipper Global Fund Flows.  Furthermore, May tax-exempt reinvestment proceeds are expected to reach approximately $34.5 billion.

Herbert J. Sims & Co. Inc. is a SEC registered broker-dealer, a member of FINRA, SIPC. The information contained herein has been prepared based upon publicly available sources believed to be reliable; however, HJ Sims does not warrant its completeness or accuracy and no independent verification has been made as to its accuracy or completeness. The information contained has been prepared and is distributed solely for informational purposes and is not a solicitation or an offer to buy or sell any security or instrument or to participate in any trading or investment strategy, and is subject to change without notice. All investments include risks. Nothing in this message or report constitutes or should be construed to be accounting, tax, investment or legal advice.
Curve Commentary: May 4, 2026

Overview

Last week the Fed voted to leave its policy rate unchanged at 3-1/2 to 3-3/4 percent citing developments in the Middle East as contributing to heightened uncertainty in their economic outlook.  Although this was the Powell’s final meeting serving as Fed chair, he has announced his intentions to remain on the Fed’s board after his term as chair ends.  Powell could potentially remain in place as a governor until that term ends in 2028.  The Fed does not meet again until June 16-17, when Kevin Warsh will host his first meeting as the new chair.

It is notable that as the market transitions from Powell to Warsh, the outlook has shifted.  At last week’s meeting, four Fed officials voted against the board’s decision with objections over language suggesting the central bank would eventually resume cutting rates.  Rising oil prices and a lack of progress in talks between the US and Iran has markets concerned that rates will remain higher for longer.  With the Fed’s dual mandate to promote maximum employment and stable prices, the markets are concerned that policymakers will focus on oil fueled inflation rather than employment.  Although the Fed funds futures market is currently anticipating that rates remain unchanged for the next 12-months, the outlook has shifted from cuts to hikes.

Insights and Strategy

Over the past week, munis and Treasuries have both sold-off with rates rising anywhere from five to 13-basis points for all but the shortest maturities.  The biggest changes have occurred around the policy sensitive two-to-three-year tenors while yields have risen about 5 bps for maturities past 14-years.  Despite these developments, investors continue be rewarded for extending out the yield curve with the steepest yields in the 18-21-year maturity range.  The long-end of the yield curve remains increasingly flat past 20-years, with a total slope of 26 bps from 21-30-years.  Due to this flat tail, municipal bond investors can currently buy maturities around 20-years that yield over 90% of the 30-year curve.

As a result of the prolific short maturity bid-wanted activity, municipal/Treasury ratios for one-year and shorter maturities are meaningfully higher than they were last week with ratios over 3% higher/cheaper.  Past five years, ratios slip a bit higher with demand extending out the curve to the longer maturities where relative yields are more appealing.  However, municipal bonds have fallen just below several important reference points along the curve.  Ratios for 10-year municipal yields remain under 70% of Treasuries, 20-year ratios are below 80% and 30-year ratios are below 90% of Treasuries.  For investors seeking to maximize curve positioning with relative value, the 18 to 21-year part of the municipal yield curve has become tempting with slopes of 12 to 13-bps per year.  Although ratios past 20-years remain attractively priced relative to Treasuries, the yield curve is very flat and does not reward extension over these longer tenors.

The Municipal new issue calendar picks-up a bit this week as US state and local governments are expected to sell over $12 billion of bonds.  Notable deals include: the City of Chicago Waterworks Revenue Bonds with $824.7 million, Texas State University System has scheduled $762.2 million, Chabot-Las Positas Community College District is expected to offer $531 million, and Indiana Municipal Power Agency is anticipated to bring $430 million to the market.  Despite record issuance this year, technical conditions remain supportive of the primary market.  Last week, municipal bond investors added approximately $615 million to municipal-bond funds, according to LSEG Lipper Global Fund Flows.  Furthermore, May tax-exempt reinvestment proceeds are expected to reach approximately $34.5 billion.

Herbert J. Sims & Co. Inc. is a SEC registered broker-dealer, a member of FINRA, SIPC. The information contained herein has been prepared based upon publicly available sources believed to be reliable; however, HJ Sims does not warrant its completeness or accuracy and no independent verification has been made as to its accuracy or completeness. The information contained has been prepared and is distributed solely for informational purposes and is not a solicitation or an offer to buy or sell any security or instrument or to participate in any trading or investment strategy, and is subject to change without notice. All investments include risks. Nothing in this message or report constitutes or should be construed to be accounting, tax, investment or legal advice.