
Overview
Last week’s decision by the Fed to leave rates unchanged was widely anticipated by the markets. As a result, rates were little changed following the meeting as evidenced by the Municipal Market Data (MMD) scale being unchanged for the day. However, the Fed kept its options open for a December hike stating that it will, “determine the policy stance appropriate to ensure a timely return of inflation to the two percent goal.” This week we will be focused on the Institute for Supply Management (ISM) monthly economic indicators on Wednesday and the Bureau of Labor Statistics’ (BLS) employment situation on Friday. In addition, midterm elections will determine outcomes for several high-stakes races with US Senate, governor, and every seat in the US House of Representatives. Voters are also being asked to consider more than $84 billion in bond sales for state and local governments. This amount exceeds levels seen in recent elections and is multiple times the $16 billion last year and above the, approximately, $81 billion on the ballot in 2024.
Insights and Strategy
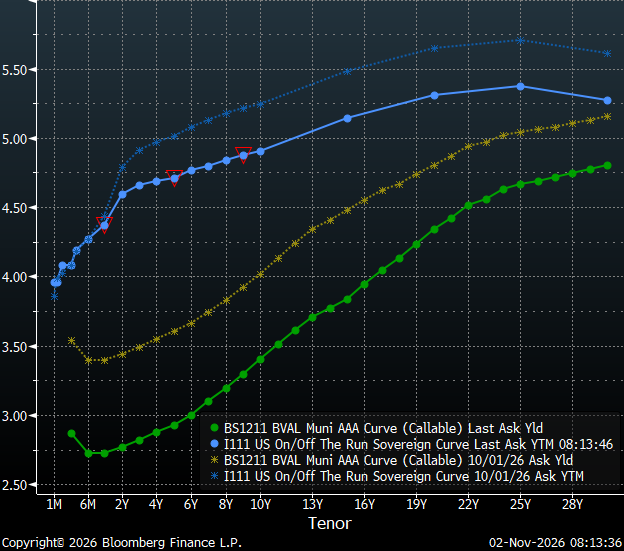
Over the past month, the Treasury curve has flattened meaningfully while munis have steepened almost 45 bps. Anxieties regarding inflation and the Fed’s rate path are apparent in the Treasury curve with significant steepness from one to two years. Although the ultra-short-end of the Treasury curve is very locked-in and has moved surprisingly little over the past month, municipals have rallied to yields that are almost 70bps lower at the 6-month tenor. The long end for both munis and Treasuries has also shifted lower, but only by around 35 bps for 30-year maturities, resulting in a steeper curve for munis and a flatter curve for Treasuries. The municipal yield curve is steepest from about 12 to 16-years with an overall slope of 58bps over this short range.
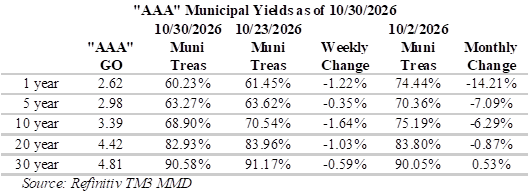
The result of recent yield adjustments is municipal/Treasury ratios that have generally declined (richer) over this past week. The largest changes occurred in the intermediate part of the yield curve, around 10-years. Furthermore, the changes over the past month have been far more dramatic, particularly around the 1-year tenor, where ratios have plummeted from almost 75% to almost 60%, this dramatic shift is due to munis rallying on the short-end, roughly 70bps, while Treasuries remained little changed. Likewise, ratios across the entire first 10-years of the yield curve are now well under 70% and 1-year ratios are just slightly over 60%. Investors seeking to maximize curve positioning with relative value can now go to the 16-year tenor and capture approximately 84% of the 30-year municipal curve with approximately half the maturity extension. Furthermore, ratios in this part of the curve are approaching 80% of Treasuries. Flattening further out the curve has made extending maturities less rewarding, but ratios are cheaper with investors capturing just over 90% of Treasuries at 30-years. Although, the yield curve is very flat over these longer tenors with a total slope of only 33 bps from 21-30-years.
US State and local governments are expected to sell $7.22 billion in new issues this week, which is up from the $6.37 billion initially offered last week. Notable deals include: United Airlines Inc. with $790 million of bonds for the Houston airport; City of St Louis Airport Revenue bonds with $472.2 million; School District of Philadelphia is scheduled to offer $450.2 million; and, City of Colorado Springs Utilities System Revenue bonds are expected to bring $401.5 million to the market. Last week, investors added $1.7 billion to municipal bond funds. However, high-yield funds experienced outflows of $546 million, marking eight consecutive weeks of outflows. Redemptions and maturities in the next 30-days narrow to an expected to total $19 billion, which is down from $19.3 billion last week, according to data compiled by Bloomberg. Furthermore, during the month of November, total monthly reinvestment proceeds in the municipal bond market are projected to reach approximately $41.7 billion.
Herbert J. Sims & Co. Inc. is a SEC registered broker-dealer, a member of FINRA, SIPC. The information contained herein has been prepared based upon publicly available sources believed to be reliable; however, HJ Sims does not warrant its completeness or accuracy and no independent verification has been made as to its accuracy or completeness. The information contained has been prepared and is distributed solely for informational purposes and is not a solicitation or an offer to buy or sell any security or instrument or to participate in any trading or investment strategy, and is subject to change without notice. All investments include risks. Nothing in this message or report constitutes or should be construed to be accounting, tax, investment or legal advice.